Best Ways to Save Money on Everyday Expenses
Saving money does not always require making huge lifestyle changes. In many cases, meaningful savings can come from making better decisions about the expenses you handle every day. Groceries, transportation, dining out, subscriptions, utilities, shopping, entertainment, and small impulse purchases can gradually take a significant portion of your income. When these expenses are not monitored, it can become difficult to understand where your money is going each month. A simple budget can help you see how much money you earn, how much you spend, and where you may be able to reduce expenses. Consumer.gov recommends listing income and expenses, comparing the two, and using the results to identify areas where spending can be changed.
The good news is that saving money on everyday expenses does not mean avoiding everything you enjoy. Instead, the goal is to become more intentional with your spending. By identifying unnecessary expenses, comparing prices, reducing waste, planning purchases, and creating better money habits, you may be able to free up more money for savings, debt payments, emergencies, or other financial goals. This guide explains some of the most practical ways to reduce everyday expenses without making your financial life unnecessarily complicated.
1. Start by Tracking Your Everyday Spending
Before trying to reduce expenses, find out where your money is actually going. Many people know their major bills but overlook smaller purchases because individual transactions may seem insignificant. A coffee, snack, delivery fee, streaming subscription, convenience-store purchase, or spontaneous online order may not appear important on its own, but repeated spending can become a meaningful monthly expense.
Try tracking every purchase for at least two to four weeks. You can use a budgeting app, spreadsheet, notebook, or your bank statements. Categorize expenses into areas such as groceries, restaurants, transportation, entertainment, shopping, subscriptions, household expenses, and miscellaneous purchases.
The Consumer Financial Protection Bureau recommends tracking spending to develop a clearer picture of spending habits and identify areas where changes may be possible.
Once you have real information, you can make decisions based on your actual spending rather than assumptions.
2. Create a Realistic Monthly Budget
A budget is one of the most useful tools for reducing everyday expenses because it gives your money a purpose before you spend it. Instead of simply checking your bank balance and spending until the next paycheck, you can decide in advance how much money should go toward bills, groceries, transportation, savings, debt, and discretionary spending.
Start by calculating your monthly take-home income. Then list your regular bills and variable expenses. Compare your total expenses with your income and identify categories where you have flexibility.
Consumer.gov recommends using a budget every month, recording spending, and comparing actual spending with the original plan.
A realistic budget should not be so restrictive that you cannot follow it. Give yourself reasonable amounts for entertainment and other personal spending while identifying areas where you can make reductions.
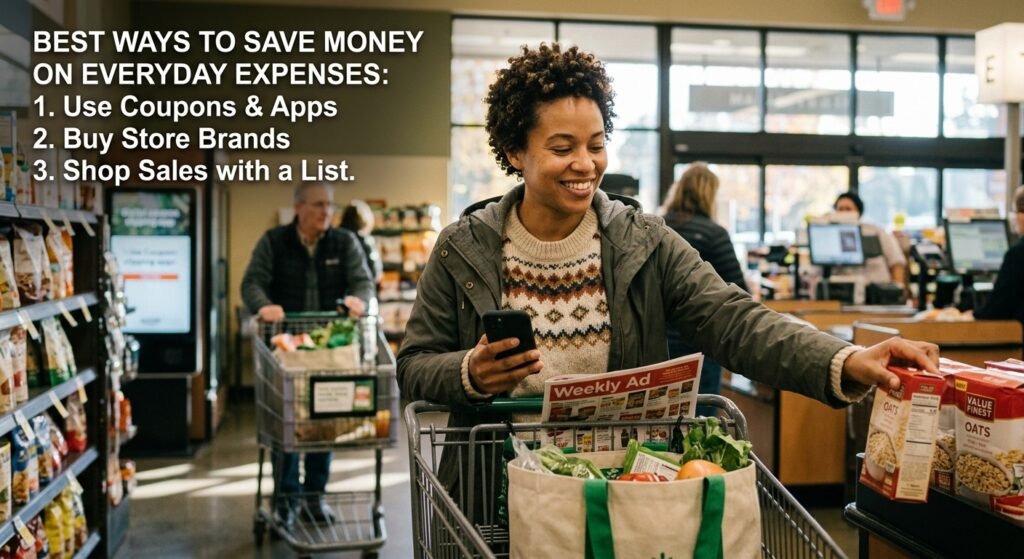
3. Reduce Grocery Spending With a Shopping Plan
Groceries are one of the easiest everyday expenses to manage because you have considerable control over what you buy. One of the simplest ways to reduce grocery costs is to create a shopping list before going to the store.
Check your refrigerator, freezer, and pantry first. Then plan several meals around ingredients you already have. Make a list of what you genuinely need and try to avoid purchasing items simply because they look attractive while shopping.
Meal planning can also reduce food waste. When you know what you intend to cook during the week, you are less likely to buy random ingredients that eventually go unused.
You can also compare prices between brands and stores, choose store-brand products when their quality and features meet your needs, and take advantage of promotions when they apply to products you were already planning to purchase.
The objective is not simply to buy the cheapest food available. The objective is to get useful value from the money you spend.
4. Cook at Home More Often
Eating out can become a significant monthly expense, especially when restaurant meals, delivery fees, service charges, and tips are combined.
Cooking at home does not mean every meal has to be complicated. Simple meals such as rice bowls, pasta, sandwiches, soups, salads, eggs, roasted vegetables, and homemade wraps can often be prepared with relatively basic ingredients.
You do not have to eliminate restaurants completely. Instead, consider choosing specific days for dining out and preparing most other meals at home.
For example, someone who regularly purchases lunch during the workweek might save money by preparing lunch at home several days each week and keeping restaurant meals as an occasional choice.
Small changes in food spending can have a noticeable effect because food is a recurring expense.
5. Reduce Food Delivery Costs
Food delivery can cost considerably more than preparing a similar meal at home. In addition to the menu price, delivery orders may include delivery charges, service fees, taxes, tips, and other costs.
If you frequently order food through delivery apps, review your spending for the previous month. You may be surprised by the total amount.
One practical strategy is to create a monthly restaurant and delivery budget. Once you reach that limit, switch to meals prepared at home until the next budgeting period.
Another option is to reduce delivery frequency rather than eliminating it. If you order four times a week, reducing that to once or twice a week may create meaningful savings while still allowing you to enjoy convenient meals.
6. Review Your Subscriptions
Subscriptions can quietly consume money because many of them are automatically charged. You may continue paying for services you rarely use simply because the monthly charge is relatively small.
Review your bank and credit card statements and identify recurring payments. Look for streaming services, apps, memberships, cloud storage, fitness subscriptions, software, gaming services, and other recurring charges.
The CFPB recommends reviewing spending and looking for services or subscriptions that are not being used.
If you have multiple services, ask yourself whether you use each one enough to justify its cost. You might cancel unused subscriptions, switch to a less expensive plan, or rotate entertainment services instead of paying for everything simultaneously.
7. Lower Your Utility Bills
Utilities are necessary expenses, but there may still be ways to reduce them.
Simple habits such as turning off unnecessary lights, adjusting heating or cooling settings, using energy-efficient appliances, and avoiding unnecessary electricity consumption can help reduce energy use.
You can also review your utility bills over several months to understand seasonal changes. If your bills suddenly increase, investigate whether there has been a change in usage, pricing, or another factor.
Saving on utilities is particularly useful because improvements can potentially continue month after month.
8. Review Your Phone and Internet Plans
Communication services are another area worth reviewing periodically.
Check your current phone and internet plans and compare the services you actually use with what you are paying for. You may be paying for more data, speed, channels, or features than you need.
Before changing a plan, make sure you understand the terms, fees, equipment requirements, contract conditions, and any potential loss of important features.
Even a modest monthly reduction can add up over a year.
9. Compare Prices Before Major Purchases
One of the simplest money-saving habits is to avoid buying the first option you see.
For expensive purchases, compare prices from multiple retailers. Check the total cost rather than only the advertised price, because shipping, taxes, warranties, accessories, and other charges can affect the final amount.
Price comparison is especially useful for electronics, appliances, furniture, insurance, travel, and other major expenses.
However, the cheapest option is not always the best value. Consider quality, durability, reliability, and the actual features you need.
The goal is to spend less without creating additional costs through poor-quality purchases.
10. Use a Waiting Period for Nonessential Purchases
Impulse purchases can make it difficult to save money. One useful strategy is to create a waiting period before buying something you do not actually need.
For smaller purchases, you might wait 24 hours. For larger purchases, consider waiting several days or even a few weeks.
During that time, ask yourself whether you genuinely need the item, whether you already own something similar, whether you can afford it within your budget, and whether you would still want it if it were not on sale.
This simple pause can reduce emotional spending and give you time to make a more deliberate decision.
11. Separate Needs From Wants
One of the most useful everyday money management skills is learning to distinguish between needs and wants.
Housing, basic food, essential transportation, utilities, and necessary healthcare are examples of expenses that may be essential. Entertainment, premium upgrades, frequent restaurant meals, and many shopping purchases are generally more flexible.
The distinction is not always absolute. A particular expense may be essential for one person but optional for another.
The important point is to understand which expenses are flexible. When money becomes tight, these categories are usually where adjustments can be made first.
The CFPB also provides financial education resources that encourage people to think about needs versus wants when making spending decisions.
12. Reduce Transportation Costs
Transportation can consume a significant part of a household budget. Fuel, insurance, maintenance, parking, public transportation, and vehicle payments can all add up.
Look for opportunities to combine errands into one trip instead of making several separate journeys. If practical, consider carpooling, public transportation, cycling, walking, or working remotely when available.
Regular vehicle maintenance can also help you avoid preventable problems. Follow the manufacturer’s recommended maintenance schedule and pay attention to warning signs.
For vehicle purchases, consider the total ownership cost rather than focusing only on the monthly payment.
13. Be Careful With Convenience Purchases
Convenience can be expensive.
Buying bottled drinks, prepared meals, snacks, premium delivery services, or other items simply because they are convenient may increase your everyday spending.
This does not mean convenience purchases are always bad. Sometimes paying for convenience saves valuable time and may be completely reasonable.
The key is to identify which convenience purchases genuinely improve your life and which ones have become automatic habits.
If you can prepare something at home in a few minutes without much effort, doing so occasionally may help reduce your monthly expenses.
14. Buy Generic or Store-Brand Products When Appropriate
Brand-name products can sometimes cost more than comparable alternatives.
For everyday items such as cleaning supplies, basic food products, paper goods, medications where appropriate, and household essentials, compare the price and product features before choosing a brand.
Check the unit price rather than simply comparing package prices. A larger package is not automatically cheaper per unit, and a smaller package can sometimes offer better value depending on promotions.
Focus on value, quality, and actual needs rather than automatically choosing the most expensive or most recognizable brand.
15. Reduce Clothing and Shopping Expenses
Clothing is another category where impulse purchases can quickly increase spending.
Before buying something new, check your existing wardrobe and ask whether you already have a similar item.
Create a shopping list for clothing just as you would for groceries. This can make it easier to focus on actual needs.
You can also consider buying durable pieces that work with multiple outfits rather than purchasing large quantities of inexpensive items that you rarely wear.
Sales can be useful, but a discount does not automatically represent a saving. If you spend $80 on something you did not need simply because it was discounted, you have still spent $80.
16. Avoid Shopping to Relieve Stress or Boredom
Emotional spending can make saving money difficult.
Some people shop when they are stressed, bored, frustrated, or looking for entertainment. Online stores make this especially easy because purchases can be completed within minutes.
If you notice this pattern, create alternative activities that do not involve spending money. Take a walk, exercise, organize your home, watch something you already have access to, read, call a friend, or work on a hobby.
Recognizing the emotional trigger behind spending can be just as important as changing the budget itself.
17. Cancel or Negotiate Unnecessary Fees
Review your bank statements and bills for recurring fees.
These might include account fees, service charges, late fees, delivery charges, or other costs.
Not every fee can be avoided, but some may be reduced or eliminated by changing account options, meeting certain requirements, switching plans, or adjusting payment habits.
The CFPB has highlighted avoiding fees and reducing bills as possible ways to free up money for savings.
Paying bills on time and monitoring account balances can also help you avoid unnecessary charges.
18. Use Cash or Spending Limits for Problem Categories
If you frequently overspend in a particular category, consider establishing a specific spending limit.
For example, you might decide that your monthly entertainment budget is $100. Once you reach that amount, you stop spending in that category until the next month.
Some people may find a cash-based system useful for categories where they struggle with impulse spending. Others may prefer digital budgeting tools or separate accounts.
The best system is the one you can consistently follow.
19. Save Money Automatically
Saving should not always depend on whatever money happens to remain at the end of the month.
Consider setting up an automatic transfer to a savings account after receiving your paycheck. Even a relatively small recurring amount can help you establish a consistent savings habit.
The CFPB has identified automatic transfers as a practical way to make saving easier and more consistent.
If you automate savings, make sure the transfer amount and timing fit your cash flow so you do not create overdrafts or problems paying essential bills.
20. Redirect the Money You Save
Saving money on everyday expenses is most useful when you give those savings a purpose.
Suppose you reduce your monthly expenses by $100. Instead of allowing that $100 to disappear into other spending, redirect it toward an emergency fund, debt repayment, a planned purchase, or another financial goal.
This creates a positive cycle. You reduce unnecessary spending, increase available cash, and then use that money to improve your financial position.
Consumer.gov also recommends including savings as part of a budget rather than treating it as whatever happens to be left over.
21. Plan for Irregular Expenses
Some expenses are not monthly, but they are still predictable.
Examples include annual insurance payments, holiday gifts, school expenses, vehicle maintenance, property-related costs, memberships, and travel.
If you ignore these expenses until they arrive, they can make one month extremely expensive.
Instead, estimate the annual cost and divide it by twelve. You can then set aside approximately that amount each month.
For example, if you expect a $600 annual expense, setting aside $50 per month would create a dedicated fund for that expense.
The exact amount should be based on your own circumstances and estimates.
22. Have a Weekly Money Check-In
You do not need to spend hours managing your finances every day.
A short weekly review can be enough to keep you aware of your spending.
Check your bank account, review recent transactions, look at upcoming bills, and compare your spending with your budget.
The CFPB recommends monitoring spending and comparing it over time to identify areas where adjustments may be possible.
A weekly check-in can also help you catch unexpected charges or subscriptions sooner.
23. Avoid Lifestyle Inflation
When your income increases, it can be tempting to immediately increase your spending.
For example, someone who receives a raise may start eating at more expensive restaurants, upgrading electronics, purchasing a more expensive car, or increasing subscription spending.
Some lifestyle improvements are perfectly reasonable, but allowing every income increase to become new monthly spending can make it difficult to build wealth.
Consider directing at least part of any income increase toward savings or financial goals before increasing discretionary spending.
This allows your financial position to improve as your income grows.
24. Use Free or Low-Cost Entertainment
Entertainment does not always need to be expensive.
Depending on where you live, free or low-cost options may include public parks, libraries, community events, hiking, home movie nights, cooking with friends, museums on free-admission days, or local activities.
You do not have to eliminate paid entertainment. Instead, mix paid activities with lower-cost alternatives.
This approach can reduce spending while still allowing you to enjoy your free time.
25. Make Saving Money a Long-Term Habit
The most effective way to save money on everyday expenses is not to rely on one dramatic financial change. Sustainable progress usually comes from repeating small decisions.
Tracking spending helps you understand your habits. Budgeting gives your income a structure. Comparing prices helps you avoid unnecessary costs. Planning meals can reduce food spending. Reviewing subscriptions can eliminate recurring charges. Automatic savings can turn small amounts into consistent progress.
A budget should also change when your circumstances change. Consumer.gov recommends using a budget every month and reviewing what you actually spent so you can make adjustments for the next month.
A Simple Everyday Money-Saving Routine
If you want a straightforward system, start with five habits.
First, track every expense for one month.
Second, identify your three biggest flexible spending categories.
Third, choose one category where you can make a realistic reduction.
Fourth, transfer the money you save toward a specific financial goal.
Fifth, review your progress at the end of every month.
For example, if you discover that restaurant spending is much higher than expected, you could establish a monthly restaurant budget. If you save $75 by reducing unnecessary meals, direct that $75 toward your emergency fund instead of spending it elsewhere.
Over time, these small decisions can become normal financial habits.
Final Thoughts
The best ways to save money on everyday expenses are usually practical rather than extreme. You do not necessarily need to stop enjoying restaurants, cancel every subscription, avoid shopping completely, or make dramatic lifestyle changes. Instead, focus on understanding where your money goes and identifying expenses that do not provide enough value for their cost.
Start by tracking your spending, creating a realistic budget, planning groceries, reducing unnecessary subscriptions, comparing prices, controlling impulse purchases, reviewing recurring bills, and automating savings. Even small changes can become meaningful when they are repeated consistently.
The purpose of saving money is not simply to spend less. It is to create more flexibility in your financial life. Money that is no longer being wasted can be redirected toward an emergency fund, debt repayment, major purchases, future goals, or long-term savings. A thoughtful spending plan can help you make those decisions with greater clarity.
Internal Linking Suggestions for Gaming Era:
- Link Smart Money Management Tips to Take Control of Your Finances when discussing overall financial habits.
- Link How to Create a Monthly Budget That Actually Works when explaining budgeting and expense tracking.
- Link How to Build an Emergency Fund From Scratch when discussing where saved money should go.
- Link How to Stop Overspending and Save More Money Every Month when discussing impulse purchases and unnecessary spending.
- Link 50/30/20 Budget Rule Explained: How to Manage Your Money Better when discussing how to organize income between needs, wants, and savings.