How to Stop Overspending and Save More Money Every Month
Overspending is one of the most common challenges people face when trying to improve their finances. You may have a regular income and still find yourself wondering where your money went at the end of every month. Small purchases, online shopping, restaurant meals, subscriptions, entertainment, convenience fees, and impulse purchases can gradually consume a significant portion of your income. Learning how to stop overspending is therefore an important part of building better money management habits.
The goal is not to stop spending money completely. Everyone needs to spend money on housing, food, transportation, bills, and other necessities. There should also be room for reasonable enjoyment. The real objective is to make your spending more intentional so that your money supports both your current needs and your future financial goals.
A successful approach to controlling spending begins with awareness. Before you can change your spending habits, you need to understand where your money is going. From there, you can create a realistic budget, identify unnecessary expenses, control impulse purchases, reduce recurring costs, and make saving money a regular part of your financial routine.
If you consistently spend more than you planned, the following strategies can help you take greater control of your monthly finances.
1. Find Out Where Your Money Is Going
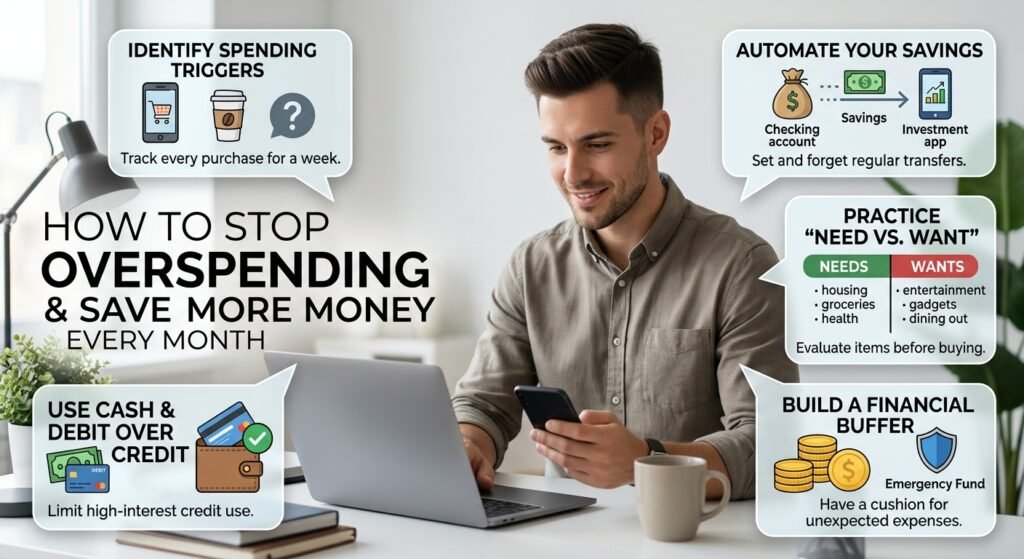
The first step in learning how to stop overspending is understanding your current spending behavior. Many people know their major monthly bills but do not have a clear picture of their smaller purchases.
Review your recent bank and credit card transactions. Look at groceries, restaurants, delivery services, shopping, subscriptions, entertainment, transportation, online purchases, and other expenses. Write everything down or use a spreadsheet or budgeting application to organize the information.
The CFPB recommends tracking spending so consumers can understand where their money goes and identify patterns that may affect their financial goals. Reviewing actual spending rather than relying on memory can provide a much clearer picture of your financial habits. (consumerfinance.gov)
You may discover that a few dollars here and there are adding up to hundreds of dollars each month. Once you can see the pattern, you can begin deciding which expenses deserve to stay and which ones can be reduced.
2. Create a Realistic Monthly Budget
A budget is one of the most effective tools for controlling spending because it gives your income a purpose before you start spending it.
Begin by calculating your monthly take-home income. Then list your essential expenses, including housing, utilities, groceries, transportation, insurance, debt payments, and other important obligations. After that, identify discretionary spending such as entertainment, dining out, shopping, hobbies, and subscriptions.
Your budget should be realistic. If you normally spend a certain amount on groceries or transportation, do not immediately set an unrealistically low limit. Instead, use your actual spending history as a starting point and identify areas where gradual reductions are possible.
Consumer.gov explains that a budget helps you plan how to spend your money each month and compare your income with your expenses. (consumer.gov)
A good budget should make you more aware of your choices without making your financial life impossible to maintain.
3. Identify Your Biggest Overspending Categories
Not all spending problems have the same impact. Instead of trying to reduce every expense at once, identify the categories where you are spending the most unnecessarily.
For some people, it may be online shopping. For others, it could be restaurants, food delivery, entertainment, travel, subscriptions, or frequent small purchases.
Review your transactions and rank your discretionary categories based on how much you spend. Focus your attention on the areas that have the greatest effect on your monthly budget.
For example, reducing a few unnecessary restaurant meals each week may save considerably more than spending time trying to eliminate a very small expense.
The goal is to make meaningful changes without creating unnecessary stress.
4. Understand the Difference Between Needs and Wants
A simple way to improve spending habits is to distinguish between needs and wants.
Needs are expenses that are necessary for basic living and important obligations. Housing, basic groceries, utilities, necessary transportation, insurance, and required debt payments are examples.
Wants are purchases that improve comfort, convenience, entertainment, or enjoyment but are not essential. Examples may include expensive restaurant meals, entertainment upgrades, unnecessary clothing, premium subscriptions, and impulse purchases.
This does not mean wants are bad. A sustainable financial plan can include discretionary spending. The important part is recognizing the difference so that wants do not consistently consume money intended for savings or essential expenses.
The CFPB also provides educational resources focused on understanding needs and wants as part of making informed spending decisions. (consumerfinance.gov)
5. Stop Impulse Shopping
Impulse purchases are one of the easiest ways to overspend. Online stores, social media advertisements, limited-time offers, personalized recommendations, and one-click checkout systems can make purchasing something almost effortless.
One useful strategy is to create a waiting period for nonessential purchases. Instead of buying immediately, wait 24 hours for smaller purchases and several days for more expensive items.
During the waiting period, ask yourself whether you actually need the item, whether it fits your budget, whether you already own something similar, and whether the purchase will interfere with a financial goal.
If you still want the item after the waiting period and it fits your budget, you can make a more deliberate decision.
Creating friction between the desire to buy and the actual purchase can help reduce impulsive spending.
6. Remove Shopping Triggers
Sometimes overspending happens because you repeatedly expose yourself to situations that encourage spending.
If promotional emails constantly tempt you to shop, unsubscribe from them. If social media advertisements encourage unnecessary purchases, reduce your exposure to shopping content. If you frequently browse online stores when you are bored, replace that habit with another activity.
You can also remove stored payment information from shopping websites. Having to enter payment details manually may create an extra moment to reconsider the purchase.
The idea is simple: make unnecessary spending less automatic.
When your environment supports your financial goals, controlling spending can become easier.
7. Use the 24-Hour Rule for Purchases
The 24-hour rule is a simple technique for reducing impulse purchases. When you want to buy something that is not necessary, wait at least one day before making the purchase.
For larger purchases, you can use a longer waiting period.
During the waiting period, consider the item’s actual value, your current budget, and whether the purchase is connected to a genuine need or temporary desire.
This technique is especially useful for online shopping because digital stores make it easy to purchase immediately. Waiting gives you time to move from an emotional reaction to a more deliberate financial decision.
8. Create a Separate Fun Money Category
Trying to eliminate all discretionary spending can make a budget difficult to maintain. Instead, consider creating a specific category for entertainment and personal spending.
Give yourself a fixed amount each month for restaurants, hobbies, movies, shopping, gaming, or other activities you enjoy.
Once that amount has been spent, wait until the next budgeting period before making additional discretionary purchases.
This approach allows you to enjoy your money without allowing optional spending to take over your entire budget.
A realistic budget is generally easier to maintain than one that completely eliminates everything enjoyable.
9. Reduce Food Delivery and Restaurant Spending
Food is an area where overspending can happen easily. Ordering delivery several times a week may appear convenient, but the total cost can become significant when menu prices, delivery charges, service fees, and tips are added.
You do not have to eliminate restaurants completely. Instead, decide how many restaurant meals or delivery orders fit into your monthly budget.
Cooking more meals at home, planning meals before grocery shopping, using ingredients you already have, and limiting convenience orders can reduce food expenses.
If you enjoy eating out, include it in your budget rather than treating it as an unplanned expense. This allows you to enjoy the experience while still maintaining control over your spending.
10. Review Your Subscriptions
Recurring subscriptions are easy to forget because the payments are often automatic. Streaming services, software, fitness memberships, apps, gaming services, and other subscriptions can quietly consume money every month.
Review your bank and credit card statements and list every recurring payment.
Ask yourself whether you still use each service. If you have not used something for several months, consider canceling it.
You can also look for lower-cost plans or rotate subscriptions instead of paying for several services simultaneously.
Reducing recurring expenses can be particularly useful because the savings continue every month.
11. Avoid Lifestyle Inflation
Lifestyle inflation occurs when your spending increases as your income increases.
For example, someone may receive a raise and immediately upgrade their car, apartment, phone, clothing, vacations, restaurants, and entertainment. Although the income is higher, there may be little improvement in savings because expenses increased at the same time.
When your income increases, consider directing part of the additional money toward savings or debt repayment before increasing your lifestyle spending.
You can still enjoy some of the additional income. The goal is simply to make sure higher earnings also improve your financial position.
12. Automate Your Savings
One of the easiest ways to save more money is to make saving automatic.
Set up a recurring transfer from your checking account to a dedicated savings account according to your pay schedule or monthly budget.
Automation can reduce the temptation to spend the money because the savings transfer happens before you have an opportunity to use it for discretionary purchases.
The CFPB identifies automatic transfers as one possible way to make saving a consistent part of your financial routine. (consumerfinance.gov)
Start with an amount that fits your budget. You can increase the amount later as your income grows or your expenses decrease.
13. Set a Specific Savings Goal
Saving money can be easier when you know exactly what you are saving for.
Instead of saying, “I want to save more,” choose a specific goal. It could be an emergency fund, a vacation, a vehicle, education, a home, retirement, or another financial objective.
Give the goal a target amount and deadline. Then calculate how much you need to save regularly.
For example, if your goal is to save $1,200 over 12 months, you would need to set aside an average of $100 per month.
A specific goal can make it easier to resist unnecessary purchases because you have a clear reason to keep the money.
14. Use Cash or Spending Limits for Problem Categories
If you repeatedly overspend in a particular category, consider creating a fixed spending limit.
For example, if you frequently overspend on restaurants, set a specific monthly amount for dining out. Once the amount is used, stop additional spending in that category until the next month.
Some people find it helpful to use cash for discretionary categories because physical money creates a visible spending limit. Others may prefer a separate debit account or budgeting application.
The best system is the one that helps you remain aware of your spending without making your financial routine unnecessarily complicated.
15. Compare Prices Before Major Purchases
Overspending does not only happen through frequent small purchases. Large purchases can have a significant effect on your finances.
Before buying expensive electronics, furniture, appliances, travel, or other major items, compare prices and features from multiple sellers.
Avoid assuming that a sale automatically means you are saving money. A discount is only useful if you actually needed the product and the purchase fits your budget.
Consider the total cost of ownership as well. Maintenance, accessories, subscriptions, insurance, and other ongoing expenses can make an apparently affordable purchase more expensive over time.
16. Use a Shopping List
Shopping without a plan can lead to unnecessary purchases, especially at grocery stores and large retailers.
Before shopping, create a list of what you actually need. Try to stick to the list unless an additional purchase is genuinely necessary.
For groceries, planning meals before shopping can make the list even more useful. Check your pantry and refrigerator first so you do not purchase items you already have.
A shopping list does not guarantee that you will never overspend, but it creates a clear purpose for the shopping trip.
17. Avoid Using Credit as Extra Income
Credit cards can be useful financial tools, but treating available credit as additional income can create serious spending problems.
A credit limit does not mean you can afford to spend that amount. Every purchase made with borrowed money may need to be repaid, and interest can increase the cost when balances are carried.
Before using credit for a purchase, consider whether you could comfortably pay for it within your financial plan.
If you already have credit card debt, consider making debt repayment a priority within your broader money management strategy.
18. Create a Weekly Spending Review
You do not have to wait until the end of the month to find out whether you overspent.
Set aside a few minutes once a week to review your transactions. Check your current account balance, recent purchases, upcoming bills, and progress toward your savings goals.
If you notice that one category is already getting close to its monthly limit, adjust your remaining spending.
Weekly reviews make it easier to correct problems early rather than discovering them after your money has already been spent.
19. Find Free or Lower-Cost Alternatives
Saving more money does not always require giving up activities you enjoy. Sometimes you can find less expensive alternatives.
Instead of expensive entertainment, consider free local events, public parks, libraries, home-based activities, or lower-cost hobbies.
Instead of purchasing something new, consider borrowing, renting, buying used, or waiting until the item is genuinely necessary.
The objective is not simply to spend less. It is to find ways to receive similar value for a lower cost.
20. Increase Your Income When Possible
Reducing expenses can help, but there is a limit to how much you can cut. Increasing income can provide additional financial flexibility.
Depending on your circumstances, you may be able to earn additional income through freelance work, part-time employment, a small business, professional development, or other legitimate opportunities.
When additional income arrives, consider assigning part of it to savings or debt repayment rather than immediately increasing spending.
Combining higher income with controlled expenses can create more room for long-term financial goals.
21. Build an Emergency Fund
An emergency fund can reduce the need to rely on credit when unexpected expenses occur.
Unexpected car repairs, medical expenses, home repairs, job disruptions, or other financial emergencies can happen even when your monthly budget is working well.
The CFPB describes an emergency fund as money set aside for unplanned expenses and notes that even small amounts can provide greater financial security. (consumerfinance.gov)
Start with an achievable savings target. As your finances improve, you can continue building the fund.
Having money reserved for emergencies can also make it easier to maintain your regular budget when unexpected costs arise.
22. Avoid Comparing Your Lifestyle With Other People
Social media can make overspending worse because it constantly exposes people to other lifestyles.
You may see expensive vacations, new cars, designer clothing, restaurants, technology, and other purchases and feel pressure to maintain a similar lifestyle.
Remember that you usually cannot see the complete financial situation behind someone else’s purchases. The important question is whether your spending supports your own goals.
Create a financial plan based on your income, responsibilities, priorities, and future objectives.
Your budget does not need to look like someone else’s.
23. Give Yourself a No-Spend Challenge
A short no-spend challenge can help you identify unnecessary spending habits.
During a defined period, such as one week, avoid nonessential purchases. Continue paying necessary bills and purchasing essential items, but avoid discretionary shopping, restaurant meals, entertainment purchases, and other optional expenses.
The goal is not necessarily to maintain a no-spend lifestyle permanently. Instead, use the challenge to identify how often you spend money out of habit.
You may discover that certain purchases were not actually necessary.
24. Make Saving Part of Your Routine
Saving money becomes easier when it becomes a normal part of your financial routine rather than something you do only when extra money is available.
Include savings in your monthly budget. Automate transfers where appropriate. Review your progress each month and increase contributions when your financial circumstances allow.
Consistency matters more than perfection.
A person who saves a manageable amount every month may develop stronger financial habits than someone who repeatedly attempts unrealistic savings targets and then gives up.
25. Review Your Progress Every Month
At the end of each month, review your spending and savings.
Look at how much you earned, how much you spent, which categories exceeded your targets, and how much you saved.
Ask yourself what worked and what needs to change.
If you overspent because of unexpected expenses, consider whether those costs should be included in future budgets. If you overspent because of impulse shopping, identify the triggers and create a strategy for the next month.
A monthly review transforms mistakes into useful information.
Common Reasons People Overspend
People overspend for many different reasons. Sometimes spending is emotional. Shopping may temporarily provide entertainment or relief from boredom or stress. Sometimes overspending happens because purchases are convenient and payment is almost effortless.
Another reason is poor planning. Without a budget, people may not know how much money is available for discretionary purchases.
Social pressure can also contribute. People may spend money to maintain a particular lifestyle or keep up with friends.
Understanding your personal reason for overspending is important because the solution depends on the cause. If convenience is the problem, create more friction around purchases. If emotional shopping is the issue, identify alternative activities. If poor planning is responsible, improve your budgeting system.
How Long Does It Take to Stop Overspending?
There is no fixed timeline for changing spending habits. Some people may notice improvements quickly after creating spending limits and removing shopping triggers, while others may need more time.
The important thing is consistency.
Do not expect every month to be perfect. Unexpected expenses can happen, and financial circumstances can change. The goal is to gradually develop better awareness and control.
If you overspend one month, review what happened and adjust your plan rather than abandoning the entire budget.
Final Thoughts
Learning how to stop overspending is not about refusing to spend money or removing every enjoyable activity from your life. It is about understanding your spending habits and making deliberate decisions about where your money should go.
Start by tracking your expenses and identifying your biggest problem areas. Create a realistic monthly budget and separate essential expenses from wants. Use waiting periods to control impulse purchases, review recurring subscriptions, plan your food spending, and create reasonable limits for discretionary purchases.
At the same time, make saving money a regular part of your financial routine. Set specific goals, automate savings when possible, build an emergency fund, and review your progress every month.
The most effective money management strategy is one you can maintain. You do not need to completely change your lifestyle overnight. A few practical adjustments can reduce unnecessary spending and create more room for savings.
Over time, better spending habits can give you greater control over your monthly income and help you work toward important financial goals. The key is to make your money decisions intentional, realistic, and consistent.