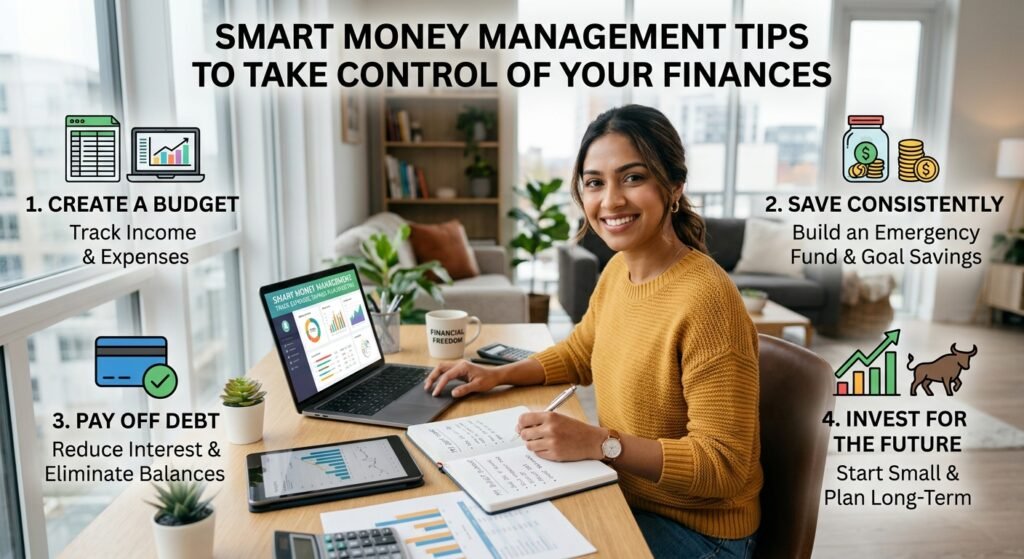
Smart Money Management Tips to Take Control of Your Finances
Managing money effectively is one of the most important skills for building a more secure financial life. Whether you have a steady salary, work for yourself, have multiple income sources, or are currently trying to reduce your expenses, understanding how to manage money can help you make better financial decisions. Good money management is not simply about earning more. It is about knowing where your money goes, controlling unnecessary spending, saving consistently, preparing for unexpected expenses, managing debt, and making realistic plans for the future.
Many people struggle with their finances because they do not have a clear system for handling their income and expenses. Money may come into a bank account and disappear through bills, subscriptions, shopping, eating out, entertainment, and other everyday expenses without a clear plan. Creating a simple financial system can make your money easier to understand and manage. The Consumer Financial Protection Bureau recommends starting by getting a realistic picture of where money comes from and where it goes, then using that information to create a workable budget and financial goals.
The good news is that you do not need to completely change your financial life overnight. Small and consistent improvements can make money management easier over time. The goal is to create habits that fit your income, responsibilities, lifestyle, and financial priorities. Here are practical money management tips that can help you take greater control of your finances.
1. Understand Your Current Financial Situation
The first step toward better money management is understanding exactly where you stand financially. Before creating a budget or setting savings goals, take some time to identify your income, regular bills, variable expenses, debts, savings, and other financial commitments. If you do not know how much money comes in or where it goes, it becomes difficult to make an effective financial plan.
Start by listing every source of monthly income. This may include your salary, freelance income, business income, side-hustle earnings, bonuses, or other regular sources. Then make a list of your expenses. Separate essential expenses such as housing, utilities, groceries, transportation, insurance, and minimum debt payments from optional spending such as entertainment, dining out, shopping, and subscriptions.
Tracking your spending for at least a month can reveal patterns that are easy to miss. You may discover that several small purchases are taking a significant portion of your income or that recurring subscriptions are costing more than expected. Understanding your financial picture gives you a starting point for making practical changes.
2. Create a Realistic Monthly Budget
Creating a monthly budget is one of the most useful money management strategies because it gives every dollar a purpose. A budget does not have to be complicated. Its main purpose is to help you compare your income with your expenses and decide how you want to use your money.
Begin with your expected monthly income and subtract your essential expenses. Then account for savings, debt payments, and flexible spending. If your expenses are greater than your income, look for areas where you can reduce spending or increase income. If you have money left over, decide how much should go toward savings, debt repayment, or another financial goal.
A realistic budget should reflect your actual lifestyle rather than an unrealistic version of it. If you normally spend money on entertainment, dining, or hobbies, completely removing those categories may make your budget difficult to maintain. Instead, assign reasonable limits. The CFPB recommends creating a working budget based on actual cash flow and updating it when income or spending patterns change.
3. Track Your Spending Regularly
A budget only works when you know whether you are following it. That is why tracking spending is an important part of effective money management. You can use a spreadsheet, notebook, budgeting application, banking tools, or another system that makes it easy to record your transactions.
Try to review your spending weekly rather than waiting until the end of the month. Regular reviews make it easier to identify problems before they become significant. For example, if you notice that your restaurant spending has already reached your monthly limit halfway through the month, you can adjust your remaining spending instead of discovering the problem after your account balance is low.
The goal of tracking expenses is not to make every purchase stressful. It is to create awareness. Once you understand your spending habits, you can make informed decisions about where your money should go.
4. Separate Needs From Wants
One of the most effective personal finance tips is learning to distinguish between needs and wants. Needs are expenses that are important for maintaining your basic lifestyle and responsibilities, while wants are purchases that may improve your comfort or enjoyment but are not essential.
Housing, basic groceries, utilities, necessary transportation, insurance, and required debt payments are generally needs. New clothes when you already have enough, expensive restaurant meals, entertainment upgrades, and impulse purchases may fall into the wants category.
This does not mean you should never spend money on things you enjoy. Good money management should allow room for enjoyment. The important thing is making sure optional spending does not consistently interfere with important financial goals.
Before making a purchase, ask yourself whether you actually need the item, whether it fits your budget, and whether buying it will interfere with a more important financial priority. Developing this habit can help reduce unnecessary spending without requiring extreme restrictions.
5. Build an Emergency Fund
An emergency fund is money set aside specifically for unexpected expenses or financial emergencies. Examples can include an unexpected repair, medical expense, job-related income disruption, or another major expense that is not part of your normal monthly budget.
Without emergency savings, an unexpected expense may force you to rely on a credit card, personal loan, or another source of borrowed money. This can make a temporary financial problem more expensive over time because of interest and fees. The CFPB describes an emergency fund as a dedicated cash reserve for unplanned expenses and notes that even small amounts of savings can provide additional financial security.
Start with an amount that feels achievable based on your current situation. You do not need to wait until you can save a large amount. Consistently transferring a manageable amount into a dedicated savings account can help you develop the habit. As your financial situation improves, you can gradually increase your emergency savings target.
6. Automate Your Savings
Saving money becomes easier when you do not have to make the decision manually every time you receive income. Consider setting up an automatic transfer from your checking account to a savings account based on your pay schedule.
For example, you could arrange an automatic transfer shortly after receiving your paycheck. Even if the amount is relatively small, consistency can make a difference over time. Automatic savings can also reduce the temptation to spend money that you intended to save.
The CFPB identifies recurring automatic transfers as one way consumers can make saving a regular part of their financial routine.
You can create separate savings goals for different purposes, such as emergency savings, travel, a vehicle, education, a home purchase, or other major expenses. Having a specific purpose can make saving more motivating than simply accumulating money without a defined goal.
7. Set Clear Financial Goals
Money management becomes more effective when you know what you are working toward. Financial goals give your money a purpose and make it easier to decide which expenses deserve priority.
Your goals can be short-term, medium-term, or long-term. A short-term goal might be saving for an upcoming expense. A medium-term goal could involve building a larger emergency fund or paying down a significant amount of debt. Long-term goals may include retirement savings, purchasing a home, or building long-term wealth.
Make your goals specific and measurable. Instead of saying, “I want to save more money,” decide how much you want to save and by when. Then calculate how much you need to set aside regularly to reach that target.
Your goals should also be realistic. Financial education is more useful when information can be converted into practical actions that fit an individual’s circumstances.
8. Control Impulse Spending
Impulse spending can quietly damage a budget because individual purchases may appear small while adding up over time. Online shopping, food delivery, entertainment purchases, and limited-time promotions can make it easy to spend money without considering the larger financial impact.
One useful strategy is to introduce a waiting period before making nonessential purchases. For smaller purchases, you might wait a day. For more expensive items, consider waiting several days or longer. During that period, ask yourself whether the purchase is necessary, whether you can afford it, and whether you would rather use the money for another financial goal.
Another strategy is to remove unnecessary shopping triggers. Unsubscribe from promotional emails, avoid browsing shopping websites without a purpose, and remove stored payment information from websites where you frequently make impulse purchases.
The objective is not to eliminate all discretionary spending. It is to make spending intentional rather than automatic.
9. Review and Reduce Recurring Expenses
Recurring expenses deserve special attention because they continue taking money from your budget every month. These can include streaming services, software subscriptions, gym memberships, premium apps, memberships, insurance costs, and other recurring charges.
Review your bank and credit card statements and identify every recurring payment. Ask whether you still use each service and whether the expense provides enough value to justify its cost.
You can also compare prices for services such as insurance, internet, phone plans, and other regular expenses. In some cases, switching providers or changing a plan may reduce your monthly costs.
Reducing a recurring expense can be particularly useful because the savings may continue month after month. A small monthly reduction can become a meaningful annual saving.
10. Manage Debt With a Clear Strategy
Debt management is an important part of personal financial management. If you have multiple debts, start by creating a complete list that includes the balance, interest rate, minimum payment, and due date for each account.
Knowing exactly what you owe allows you to create a repayment strategy. Two commonly discussed approaches are the highest-interest method, which prioritizes debts with the highest interest rates, and the debt snowball method, which focuses on smaller balances first. The CFPB includes both approaches among common debt-reduction strategies.
Whichever approach you choose, continue making required minimum payments while directing additional money toward your selected priority debt. Avoid taking on unnecessary new debt while working on your repayment plan.
If your debt situation becomes difficult to manage, consider seeking qualified financial or credit counseling. The CFPB notes that credit counseling organizations can help consumers review their finances, develop budgets, and create debt-management plans.
11. Pay Bills on Time
Late payments can lead to fees and other financial consequences, so organizing bill payments should be a core part of your money management system. Create a list of your recurring bills and their due dates.
You can use a calendar, spreadsheet, banking alerts, or automatic payments where appropriate. The important thing is having a system that reduces the chance of forgetting a payment.
If the timing of your income and bills creates cash-flow problems, review the dates and consider whether any providers or creditors offer alternative due dates or payment arrangements. The CFPB recommends looking at the timing of income and expenses when creating a working cash-flow budget.
12. Build Better Credit Habits
Credit can affect your ability to borrow money and may influence the terms you receive on certain financial products. Managing credit responsibly is therefore another important part of overall financial management.
Pay attention to your payment history, keep track of balances, and avoid applying for credit unnecessarily. Review your credit reports periodically and check for inaccurate information.
Good credit habits are not created by one action. They develop through consistent financial behavior over time. Treat credit as a financial tool rather than an extension of your income, and understand the costs associated with borrowing before taking on new debt.
13. Keep Your Financial Accounts Organized
Disorganization can make money management unnecessarily difficult. If you have multiple bank accounts, credit cards, loans, investment accounts, or savings goals, create a simple system for keeping track of them.
Maintain a secure record of account information, payment dates, balances, and financial goals. Review your accounts regularly so you can identify unexpected charges or changes.
You can also organize your finances around specific purposes. For example, one account could be used for everyday spending while another is dedicated to emergency savings. The exact structure depends on your circumstances, but the goal is to make your money easier to understand and manage.
14. Review Your Finances Every Month
Money management should be an ongoing process rather than something you do once. Set aside time each month to review your income, expenses, savings, debts, and progress toward financial goals.
Look at which parts of your budget worked well and which areas need adjustment. If grocery expenses increased, transportation costs changed, or your income changed, update your budget accordingly.
A monthly financial review can also help you recognize positive progress. Perhaps you reduced unnecessary spending, increased your savings contribution, paid down debt, or reached an important financial milestone. Recognizing progress can help you stay motivated.
15. Increase Your Income When Possible
Reducing expenses is only one part of money management. Increasing income can also improve your financial flexibility. Depending on your situation, this could involve developing new professional skills, negotiating compensation, taking on freelance work, starting a small side business, or finding other legitimate ways to earn additional income.
Extra income should have a purpose. Instead of automatically increasing lifestyle spending, consider directing some of the additional money toward emergency savings, debt repayment, or long-term financial goals.
Increasing income does not automatically solve financial problems if spending increases at the same rate. Combining higher income with responsible spending habits can create more room for saving and financial progress.
16. Avoid Lifestyle Inflation
Lifestyle inflation happens when spending increases as income increases. Getting a raise or earning additional money can create opportunities, but automatically upgrading every part of your lifestyle may prevent you from building financial security.
When your income increases, consider keeping some existing expenses unchanged and directing a portion of the additional income toward savings or debt repayment. You can still improve your lifestyle, but doing so intentionally can help prevent your financial goals from constantly moving further away.
The key is finding a balance between enjoying your current income and preparing for future needs.
17. Use Financial Tools Carefully
Budgeting applications, spreadsheets, banking alerts, savings automation, and financial calculators can make money management easier. The best tool is not necessarily the most complicated one. It is the one you will actually use consistently.
Choose a system that allows you to monitor income, expenses, bills, savings, and debt without creating unnecessary complexity. Review your financial tools regularly and make sure you understand any fees, privacy considerations, or account permissions before using third-party financial services.
Technology can support good financial habits, but it cannot replace them. A budgeting application is useful only when you regularly review the information and make decisions based on it.
18. Give Yourself a Reasonable Spending Allowance
Strict budgeting can sometimes become difficult to maintain when every purchase feels restricted. One way to make your financial plan more sustainable is to include a reasonable amount of discretionary spending.
Set aside money for activities you enjoy, such as entertainment, dining out, hobbies, or personal purchases. As long as the amount fits within your overall budget, spending on enjoyment does not automatically mean you are managing money poorly.
The goal of a budget is to help you make informed choices. A sustainable financial plan should balance today’s needs with tomorrow’s goals.
19. Prepare for Large and Irregular Expenses
Some expenses do not happen every month, but that does not mean they should surprise you. Annual insurance payments, holiday spending, school expenses, vehicle maintenance, property costs, and other irregular expenses can create financial pressure if you do not plan for them.
Review the previous year’s spending and identify large expenses that are likely to happen again. Estimate the annual cost and divide it into monthly savings targets.
For example, if you expect a $1,200 annual expense, setting aside $100 per month would allow you to prepare for it gradually. The exact amount depends on your circumstances, but the principle is simple: plan for predictable expenses before they arrive.
20. Make Money Management a Long-Term Habit
The most important money management tip is to think beyond a single month. Financial improvement comes from repeated decisions rather than one perfect budget.
You will have months when expenses are higher than expected. You may have unexpected bills, changes in income, or financial priorities that require adjustments. That does not mean your entire financial plan has failed. Review what happened, make reasonable changes, and continue moving forward.
Money management is ultimately about creating a system that helps you make thoughtful decisions. Tracking your spending, creating a realistic budget, saving regularly, controlling unnecessary expenses, managing debt, and setting clear goals can all contribute to stronger financial habits.
Final Thoughts on Smart Money Management
Taking control of your finances starts with understanding your current situation and creating a realistic plan. You do not need a perfect income, a complicated investment strategy, or an extreme savings routine to begin improving your money management skills. Start by tracking your money, creating a budget, identifying unnecessary expenses, building emergency savings, and setting financial goals that match your circumstances.
As your habits improve, you can focus on more advanced areas such as debt reduction, credit management, retirement planning, investing, and long-term wealth building. The CFPB’s consumer resources similarly emphasize tracking income and spending, managing bills, building savings, handling debt, and setting financial goals as practical areas of financial management.
Remember that effective money management is personal. A strategy that works for one household may not work for another because income, expenses, responsibilities, debt, and financial goals are different. Instead of copying someone else’s financial routine exactly, use these money management tips as a framework and adjust them to your own situation.
The most valuable step is simply to start. Track where your money is going, make a plan for where you want it to go, and review your progress regularly. Small improvements can become powerful habits when you repeat them consistently. With a practical budget, disciplined spending, regular saving, thoughtful debt management, and clear financial goals, you can build a stronger foundation for your financial future.