How to Manage Your Money When Living Paycheck to Paycheck
Living paycheck to paycheck can make managing money feel difficult. When most or all of your income is already committed to housing, food, transportation, utilities, debt payments, and other regular expenses, there may seem to be very little room for savings or unexpected costs. A budget can help you understand exactly how much money comes in and where it goes, while a cash flow plan can help you match the timing of income with the timing of your bills. Consumer.gov explains that a budget can help prevent running out of money before the next paycheck and can also create room for savings and financial goals.
Living paycheck to paycheck does not necessarily mean that someone is irresponsible with money. Housing costs, transportation, family responsibilities, debt, inflation, irregular income, and other circumstances can all affect the amount of money available after essential expenses. The goal is therefore not to feel guilty about your financial situation. The goal is to understand your cash flow, prioritize your expenses, reduce avoidable spending where possible, and gradually create more financial breathing room.
The following strategies can help you build a practical money management system even when your current income is already heavily committed.
1. Understand Exactly How Much Money You Bring Home
The first step toward better money management is knowing your actual take-home income. Do not build your budget around your gross salary if taxes, insurance, retirement contributions, or other deductions are taken from your paycheck. Your budget should generally be based on the money that is actually available to spend and save.
If you receive a regular paycheck, review your recent pay statements and calculate your typical take-home income. If your income changes from paycheck to paycheck, look at several months of income rather than assuming every month will be the same.
Consumer.gov recommends listing your income and expenses when creating a budget so you can compare the money coming in with the money going out.
If your income is irregular, consider creating your regular spending plan around a conservative estimate rather than assuming that your highest-income month will repeat every month.
2. Track Every Expense
When money is tight, small expenses matter because there may be very little unused income available.
For at least one month, record every expense. Include rent or mortgage payments, utilities, groceries, transportation, insurance, debt payments, subscriptions, entertainment, online purchases, restaurant meals, and small purchases.
Do not ignore expenses simply because they are inexpensive. A $5 purchase may not seem important, but several small purchases every week can become a significant monthly amount.
The CFPB recommends reviewing spending carefully and including less frequent expenses so that your budget reflects your actual financial situation rather than an idealized version of it.
Once you have a complete picture, you can identify which expenses are essential, which are flexible, and which can potentially be eliminated.
3. Create a Paycheck-Based Budget
A traditional monthly budget can sometimes be difficult for people who are paid weekly, biweekly, or on another schedule.
If you frequently run out of money before payday, consider creating a paycheck-based budget. Instead of only asking, “How much can I spend this month?” ask, “Which expenses need to be paid before my next paycheck?”
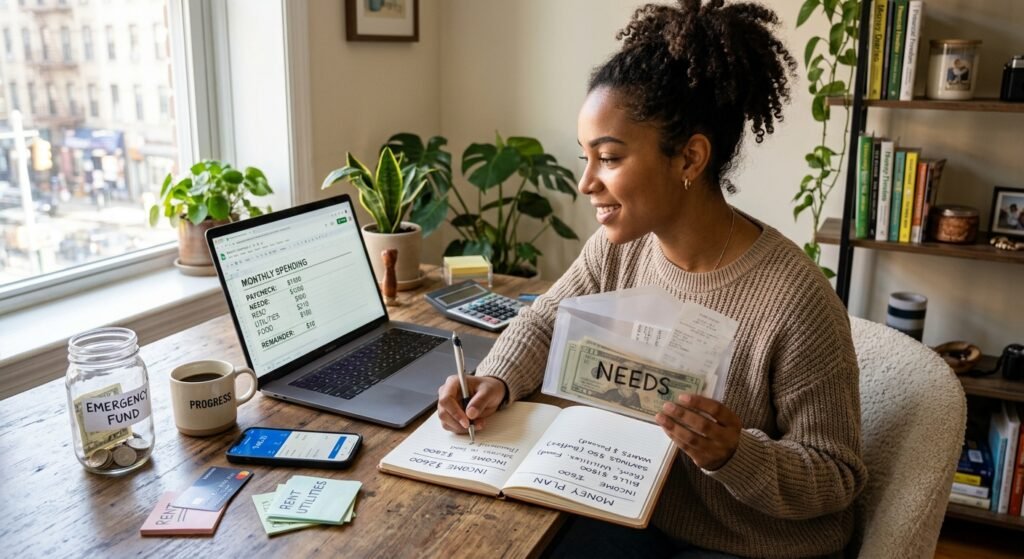
For example, if you receive $1,500 every two weeks, list the bills and necessary expenses that must be covered during that two-week period. Allocate money for those expenses first and then determine how much remains for groceries, transportation, savings, and discretionary spending.
This approach makes your budget more closely connected to your actual cash flow.
The CFPB explains that cash flow involves the timing of money coming in and money going out, and tracking that timing can help people identify opportunities to adjust spending and savings.
4. Prioritize Essential Expenses
When money is limited, not every expense can receive the same priority.
Start with expenses that protect your basic needs and ability to work. Depending on your circumstances, these may include housing, essential utilities, food, transportation, insurance, healthcare, and required debt payments.
After identifying these expenses, look at discretionary categories such as entertainment, restaurant meals, shopping, premium subscriptions, and other optional spending.
This does not mean that you can never spend money on enjoyable activities. It simply means that your essential expenses should be accounted for before discretionary purchases.
Creating this priority system can make difficult financial decisions easier because you know which expenses should come first.
5. Build a Bill Calendar
If you are paid regularly but still find yourself short of money at certain points during the month, the problem may partly involve the timing of your bills.
Create a calendar showing each bill, its amount, and its due date. Then add your expected paydays.
This lets you see exactly when money will enter your account and when major payments will leave it.
The CFPB notes that people who live paycheck to paycheck may experience cash flow problems when bill due dates do not align with paydays. It also suggests contacting creditors or service providers to ask whether due dates can be adjusted when appropriate.
Not every company will change a due date, but asking can sometimes improve the timing of your cash flow.
6. Separate Fixed and Flexible Expenses
Your expenses can generally be divided into different categories.
Fixed expenses are costs that tend to remain relatively stable, such as rent, a car payment, or certain insurance premiums.
Flexible expenses can change from month to month. These might include groceries, dining out, entertainment, shopping, and some utility costs.
This distinction matters because flexible expenses often provide more immediate opportunities to adjust your budget.
If your income is not enough to cover essential fixed expenses, cutting small discretionary purchases alone may not solve the problem. In that situation, you may need to examine larger costs, negotiate bills, explore additional income, or seek appropriate financial assistance.
7. Reduce Your Biggest Flexible Expenses First
Instead of trying to save money on everything at once, identify your largest flexible expenses.
For example, if you discover that restaurants and food delivery cost $500 per month, reducing that category may create more savings than spending hours trying to eliminate small purchases.
Similarly, if transportation costs are unusually high, look at fuel, parking, commuting, insurance, or other transportation expenses.
Focus your effort where the potential impact is greatest.
A realistic reduction in one large category can sometimes be easier to maintain than dozens of tiny restrictions across your entire lifestyle.
8. Plan Your Grocery Spending
Food is an essential expense, but there are often ways to make grocery spending more predictable.
Create a weekly or biweekly grocery budget based on your income schedule. Before shopping, check what you already have at home and plan meals around those ingredients.
Make a shopping list and try to avoid unnecessary purchases.
Compare unit prices, consider store-brand products when appropriate, and avoid buying large quantities simply because something appears to be discounted.
Meal planning can also reduce food waste because you are purchasing ingredients with a specific purpose.
The goal is not to make your grocery budget unrealistically low. The goal is to create a spending amount that supports your household while reducing unnecessary waste.
9. Limit Restaurant and Delivery Spending
Restaurants and food delivery can be particularly challenging when living paycheck to paycheck because the cost of a single meal can be much higher than the cost of preparing food at home.
You do not necessarily need to eliminate restaurants completely.
Instead, establish a specific amount for dining out and track it throughout the month.
For example, you might decide that you can spend $75 or $100 per month on restaurants. Once the amount has been used, you wait until the next budget period.
This creates a clear boundary without requiring you to completely remove enjoyment from your budget.
10. Review Subscriptions and Recurring Charges
Recurring payments can be easy to overlook because they are often automatically deducted.
Review your bank and credit card statements and make a list of all subscriptions and memberships.
Ask yourself how frequently you use each service. If you rarely use something, consider canceling it. You may also be able to switch to a lower-cost plan.
The CFPB recommends reviewing recurring services and subscriptions when looking for ways to reduce expenses, particularly during periods of financial pressure.
Even small monthly reductions can become useful when your budget is already tight.
11. Create a Small Emergency Fund
When living paycheck to paycheck, saving for emergencies can feel impossible. However, you do not need to begin with a large savings target.
Start with a small amount that fits your current situation.
Your first goal might be $100, $250, $500, or another realistic amount. Once you reach it, you can gradually increase the target.
The CFPB specifically notes that even people living paycheck to paycheck may benefit from putting aside small amounts for unexpected expenses.
The purpose of the initial emergency fund is to create a financial buffer. Eventually, you may want a larger reserve based on your essential expenses and circumstances.
12. Automate Small Savings When Possible
Automatic savings can make saving easier because you do not have to remember to transfer money every time you receive a paycheck.
If your budget allows it, set up a small recurring transfer from your checking account to a savings account.
This might be $10, $20, $25, or another amount you can consistently afford.
The CFPB identifies automatic transfers and splitting direct deposits between accounts as strategies that can make saving more consistent. It also recommends monitoring your balance so an automatic transfer does not result in overdraft fees.
If your income changes, adjust the amount rather than allowing the transfer to cause financial problems.
13. Use the “Save First” Approach Carefully
The idea of paying yourself first can be useful, but it needs to be realistic when your finances are extremely tight.
If you have enough income to cover essential expenses, putting a small amount into savings immediately after receiving your paycheck can help establish the habit.
However, you should not automatically transfer an amount that leaves you unable to pay essential bills.
A sustainable savings habit is more useful than an aggressive target that causes overdrafts or forces you to borrow money later in the month.
14. Avoid Using Credit Cards to Cover Everyday Shortfalls
Credit cards can be useful financial tools, but using them repeatedly to cover basic expenses when your income does not cover your spending can create a cycle of increasing balances and interest costs.
If you consistently reach the end of each month with a credit card balance because your income is insufficient for your essential expenses, focus on understanding the underlying cash flow problem.
Review your budget and determine whether the issue comes from discretionary spending, high fixed costs, debt payments, irregular expenses, or insufficient income.
Reducing new borrowing can become difficult if the underlying gap is not addressed.
15. Make a Debt Repayment Plan
Debt payments can take up a substantial portion of monthly income.
Start by listing each debt, its balance, interest rate, minimum payment, and due date. This gives you a clear picture of your obligations.
Continue making required minimum payments according to your agreements while deciding how to direct any additional money toward debt.
If your budget is extremely tight, avoid setting a repayment amount that leaves you unable to cover essential expenses.
You can also contact lenders or creditors if you are struggling to make payments and ask what options may be available. Any changes should be understood carefully before agreeing to them.
16. Plan for Irregular Expenses
One reason people living paycheck to paycheck can feel constantly behind is that some expenses are predictable but do not happen every month.
Examples include annual insurance payments, vehicle maintenance, school expenses, holiday spending, medical costs, or periodic memberships.
Instead of treating these expenses as emergencies, estimate the annual cost and divide it into smaller monthly amounts.
For example, if you expect a $600 annual expense, setting aside approximately $50 per month could help prepare for it.
The CFPB recommends looking back over several months to identify less frequent expenses that may otherwise be missed in a monthly budget.
17. Stop Treating Predictable Expenses as Emergencies
A broken water heater may be an emergency. An annual insurance payment that happens every year is not an unexpected expense.
Understanding this distinction can improve your financial planning.
Create separate savings categories for predictable expenses whenever possible. Your emergency fund should be reserved for genuinely unexpected situations rather than expenses you knew were coming.
This approach can make your emergency savings last longer and reduce financial surprises.
18. Try a No-Spend Period
A no-spend challenge can help you identify unnecessary spending habits.
For a limited period, such as one week, avoid nonessential purchases while continuing to pay necessary bills and purchase essential food and supplies.
The purpose is not to permanently stop spending. Instead, use the exercise to understand how often you make purchases out of habit.
After the challenge, identify which spending behaviors you want to change permanently.
19. Use a Weekly Spending Limit
Monthly budgets can sometimes feel too distant when money is tight.
A weekly spending limit can make your budget easier to manage.
Suppose you have $300 available for groceries, transportation, and flexible spending after accounting for your major bills. Instead of viewing the entire amount as immediately available, divide it into weekly targets.
This can reduce the chance of spending too much during the first week and having almost nothing available before your next paycheck.
Your actual limits should be based on your income, expenses, and payment schedule.
20. Create a “Bare-Bones” Budget
A bare-bones budget is a temporary version of your budget that focuses on essential expenses.
It can be useful during periods of unemployment, reduced hours, unexpected expenses, or other financial pressure.
List only the expenses you genuinely need to maintain housing, food, essential transportation, utilities, healthcare, insurance, and other necessary obligations.
Then temporarily reduce or pause optional spending.
You do not necessarily need to live under a bare-bones budget permanently. It can simply be a tool for stabilizing your finances during a difficult period.
21. Increase Your Income if Possible
Reducing expenses is only one side of improving your finances.
If you have already cut unnecessary spending and still cannot cover your essential expenses, increasing income may be necessary.
Depending on your circumstances, this could involve overtime, freelance work, part-time employment, selling unused possessions, developing a new skill, or seeking a higher-paying position.
The appropriate option depends on your available time, skills, responsibilities, and local opportunities.
Even a modest increase in income can create more room for savings or debt repayment when expenses are already tightly controlled.
22. Use Windfalls Strategically
Occasional extra money can provide an opportunity to improve your financial position.
Examples might include a tax refund, work bonus, cash gift, freelance payment, or proceeds from selling unused items.
You could use part of the money for an immediate need and direct the rest toward an emergency fund or debt.
The CFPB specifically identifies one-time opportunities, such as tax refunds and cash gifts, as potential ways to build emergency savings.
A windfall does not have to disappear through impulse spending.
23. Avoid Lifestyle Inflation
If your income increases, it can be tempting to immediately increase your spending.
However, if you are trying to escape the paycheck-to-paycheck cycle, consider directing some of your additional income toward financial goals before upgrading your lifestyle.
For example, if you receive a raise, you might allocate part of the increase toward emergency savings and debt repayment while using the remainder for lifestyle improvements.
This allows your financial position to improve without requiring you to eliminate every enjoyable expense.
24. Review Your Budget Every Week
A budget is not something you create once and forget.
When money is tight, regular reviews are especially important.
Once a week, check your current balance, upcoming bills, recent spending, and remaining budget for groceries, transportation, and other categories.
Compare your actual spending with your plan and make adjustments before a small problem becomes a major one.
Consumer.gov recommends using a budget each month, recording spending, and using the results to improve the next month’s plan.
25. Focus on Cash Flow, Not Just Monthly Income
Someone can have enough income on paper but still experience financial stress because bills arrive before their next paycheck.
This is why cash flow matters.
Write down your paydays and major expenses on a calendar. Identify weeks where several payments occur at once.
If possible, explore whether certain bill due dates can be moved to better align with your income schedule. The CFPB specifically discusses adjusting bill due dates as one possible cash-flow strategy.
Improving timing will not increase your income, but it can make the money you already have easier to manage.
26. Build a Financial Buffer One Step at a Time
The ultimate goal is to create more space between your income and expenses.
That space might initially be only $20 per paycheck. Later, it could become $50, $100, or more.
Do not underestimate small improvements.
If you reduce unnecessary expenses by $75 per month and save that money, you could have $900 after twelve months, before considering any interest. If you combine that with occasional extra income, the progress can be faster.
The exact numbers will vary, but the principle remains the same: create a small gap between what comes in and what goes out, then protect that gap.
A Simple Paycheck-to-Paycheck Money Management System
If you want a simple system to follow, start with these steps.
First, calculate your actual take-home income.
Second, list all essential bills and expenses.
Third, identify the due date of every major bill.
Fourth, match each bill to the paycheck that will cover it.
Fifth, set realistic limits for groceries, transportation, and discretionary spending.
Sixth, reduce unnecessary recurring expenses.
Seventh, create a small emergency savings goal.
Eighth, automate a small savings contribution if your cash flow allows it.
Ninth, review your spending every week.
Finally, direct future income increases and occasional windfalls toward building financial stability.
This system is not designed to create an overnight transformation. It is designed to help you understand your money and gradually improve your position.
Example of a Paycheck-Based Budget
Imagine someone receives $1,800 every two weeks.
Instead of thinking about the full $3,600 as immediately available for the month, they could assign each paycheck to upcoming expenses.
The first paycheck might cover a portion of housing, utilities, groceries, transportation, and savings.
The second paycheck might cover the remaining housing costs, debt payments, insurance, groceries, and other upcoming expenses.
The exact allocation would depend entirely on the person’s actual bills and due dates.
The important principle is to assign money before spending it. This can make it easier to avoid accidentally using money that is already needed for an upcoming bill.
What If Your Expenses Are Higher Than Your Income?
Sometimes the problem is not poor budgeting. Sometimes the numbers simply do not work.
If your essential expenses are consistently higher than your income, cutting small purchases may not be enough.
Consumer.gov advises that when expenses exceed income, you should review your budget to identify expenses that can be changed.
Start by examining your largest costs. Housing, transportation, debt, insurance, and childcare can have a much greater impact than small discretionary purchases.
You may need to consider options such as changing housing arrangements, refinancing or restructuring certain obligations where appropriate, reducing transportation costs, increasing income, or seeking qualified assistance.
The key is to identify the actual source of the deficit rather than blaming every small purchase.
How to Break the Paycheck-to-Paycheck Cycle
Breaking the paycheck-to-paycheck cycle usually happens gradually.
First, understand your numbers.
Then create a realistic budget.
Next, stabilize your cash flow and reduce unnecessary expenses.
After that, establish a small emergency fund.
Once you have some savings, work on reducing expensive debt and increasing the gap between income and expenses.
As your financial position improves, increase your emergency savings and work toward longer-term financial goals.
There is no single timeline that applies to everyone. Your progress will depend on income, expenses, debt, family responsibilities, and other circumstances.
Final Thoughts
Learning how to manage your money when living paycheck to paycheck starts with understanding your actual cash flow. Instead of waiting for payday and hoping there is enough money left, create a plan for each paycheck. Track your expenses, prioritize essential bills, control flexible spending, prepare for irregular costs, and review your budget regularly.
Even when money is tight, small changes can create progress. A $20 savings contribution, a reduced subscription bill, fewer restaurant meals, or better bill timing may seem minor individually, but consistent improvements can gradually create more financial breathing room.
Most importantly, do not assume that living paycheck to paycheck means you cannot save. The CFPB specifically notes that even small amounts can provide some financial security and that cash-flow management can be especially useful for people whose income and expenses are tightly matched.
Your first goal does not have to be becoming financially independent overnight. Start by making sure you know where your money goes, then work toward creating even a small amount of money left over after essential expenses. From there, you can build an emergency fund, reduce debt, strengthen your savings habits, and gradually work toward greater financial stability.
Internal Linking Suggestions for Gaming Era:
- Link How to Create a Monthly Budget That Actually Works when explaining how to create a realistic spending plan.
- Link How to Build an Emergency Fund From Scratch when discussing emergency savings.
- Link How to Stop Overspending and Save More Money Every Month when discussing spending reductions.
- Link Best Ways to Save Money on Everyday Expenses when discussing ways to reduce recurring and flexible costs.
- Link Smart Money Management Tips to Take Control of Your Finances when discussing long-term money management habits.
- Link 50/30/20 Budget Rule Explained: How to Manage Your Money Better as an additional budgeting resource, while noting that the percentages may need to be adapted when essential expenses are already consuming most income.