Saving Plans vs. Investment Plans: What’s the Difference?
Saving money and investing money are two important parts of personal financial planning, but they are not the same thing. Many people use the terms “saving” and “investing” interchangeably, even though they serve different purposes and involve different levels of risk. Understanding the difference between saving plans and investment plans can help you make better decisions about how to manage your money, whether you are a student, young professional, family member, or someone planning for retirement.
A saving plan generally focuses on protecting money and keeping it available for short-term or unexpected needs. An investment plan, on the other hand, usually focuses on growing money over a longer period by putting it into assets that may increase in value or generate income. Because investments can rise and fall in value, they normally involve more risk than traditional savings.
The right approach does not necessarily mean choosing saving plans over investment plans or investments over savings. In many cases, people need both. Savings can provide financial stability and access to cash, while investments can potentially support long-term wealth-building goals. The key is understanding when and why each strategy may be appropriate.
What Is a Saving Plan?
A saving plan is a structured approach to setting aside money for future expenses or financial goals. The money is typically kept in a savings account, deposit account, cash reserve, or another relatively accessible savings product.
The main purpose of a saving plan is usually financial security rather than maximizing growth. People commonly use savings for emergencies, upcoming purchases, education expenses, vacations, household expenses, or other goals that may occur within a relatively short period.
For example, someone may decide to save a fixed amount every month for a new laptop. Another person may create an emergency fund to cover unexpected expenses. A family may save money for school fees, a vehicle, or a future home deposit.
A saving plan can be as simple as transferring a fixed amount from a checking account into a savings account every month. What makes it a plan is the combination of a specific goal, regular contributions, and a consistent strategy.
What Is an Investment Plan?
An investment plan is a strategy for putting money into assets with the objective of achieving long-term financial growth or generating income. Depending on the investor’s country, financial situation, risk tolerance, and goals, investments can include stocks, bonds, mutual funds, exchange-traded funds, real estate, or other investment products.
Unlike ordinary savings, investments can fluctuate in value. An investment may increase in value, but it can also lose value. This means investors need to understand risk and be prepared for periods when their investments decline.
Investment plans are generally more suitable for goals that are several years away. Retirement planning is a common example. Someone who does not need their money for many years may have more ability to tolerate short-term market fluctuations than someone who needs the money next month.
The purpose of investing is generally to give money an opportunity to grow over time, although returns are never guaranteed.
Saving Plans vs. Investment Plans
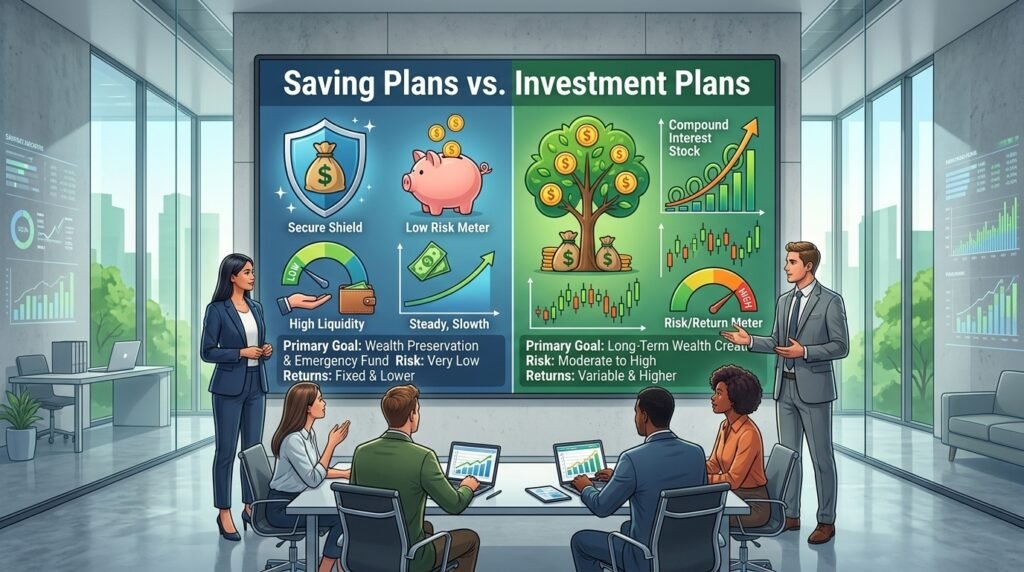
The main difference between saving and investing is their purpose and risk profile. Saving generally emphasizes safety, accessibility, and preservation of money. Investing generally emphasizes potential long-term growth, with a greater possibility of losing some or all of the money depending on the investment.
Savings are often used for short-term financial goals, while investments are generally associated with medium- or long-term objectives.
Another important difference is accessibility. Savings accounts and similar products are typically designed to make money relatively easy to access. Investments may be less convenient to sell or may fluctuate in value when you need to withdraw the money.
For example, keeping money for an emergency in an accessible savings account can provide greater certainty than investing that money in a volatile asset. If the investment falls in value at the same time an emergency occurs, you might have to sell it for less than you originally invested.
Difference in Risk
Risk is one of the most important differences between saving plans and investment plans.
Traditional savings products are generally designed to protect the deposited money, although the exact protections depend on the financial institution and country. The interest earned may also be relatively predictable depending on the product.
Investments can have substantially different risk levels. A diversified investment portfolio may contain several types of assets, while an individual stock can experience significant price changes.
The possibility of higher returns comes with the possibility of losses. Therefore, investment decisions should consider your financial goals, time horizon, ability to tolerate losses, and knowledge of the investment.
Difference in Returns
Saving and investment products can generate different types and levels of returns.
A savings account may pay interest on the money deposited. The interest rate can vary depending on the financial institution, account type, economic conditions, and other factors.
Investments may generate returns through price appreciation, dividends, interest payments, rental income, or other sources depending on the asset.
However, higher potential returns generally involve higher risks. There is no universal investment that guarantees high returns without risk.
People should be cautious about financial opportunities that promise unusually high or guaranteed returns while claiming there is little or no risk.
Short-Term Goals and Savings
Saving plans are often more appropriate for short-term financial goals.
Suppose you need money for a tuition payment in six months. You probably want the money to be available when the payment is due. Placing that money into an investment whose value could fall substantially during that period may create unnecessary uncertainty.
The same principle applies to emergency funds. If you may need the money unexpectedly, accessibility and stability are important considerations.
Other short-term goals can include purchasing household equipment, paying annual expenses, taking a planned trip, or covering an upcoming education expense.
Long-Term Goals and Investments
Investment plans can be useful for long-term goals because longer time horizons can provide more opportunity for investments to experience growth and recover from temporary declines.
Retirement is one of the most common examples. A person who is decades away from retirement may have a longer period to invest and potentially benefit from compound growth.
Long-term investing requires patience. Markets can experience periods of strong growth as well as declines. Investors who have long-term goals generally need to understand that short-term market movements are normal and that investment values are not guaranteed.
The appropriate investment strategy depends on factors such as age, financial circumstances, goals, risk tolerance, and investment horizon.
What Is an Emergency Fund?
An emergency fund is a type of savings designed to cover unexpected expenses.
Examples can include emergency travel, urgent repairs, medical expenses, temporary loss of income, or other unforeseen costs.
The appropriate emergency fund size depends on a person’s income, expenses, employment situation, family responsibilities, and other circumstances.
The important principle is that emergency money should generally be accessible and relatively stable. It is usually not appropriate to treat highly volatile investments as a substitute for emergency savings.
Building an emergency fund can also reduce the need to rely on expensive debt when an unexpected expense occurs.
Can You Have Both a Saving Plan and an Investment Plan?
Yes. In fact, many people use both as part of an overall financial strategy.
Savings can provide short-term financial security while investments can support long-term financial goals.
For example, someone might maintain an emergency fund in a savings account while contributing regularly to a retirement investment account.
Another person might save for a car while investing separately for a long-term goal such as retirement.
Using both strategies allows you to assign different types of money to different purposes.
How Much Should You Save Before Investing?
There is no single amount that applies to everyone. The appropriate balance depends on your income, expenses, debt, financial responsibilities, and goals.
Many people prioritize building an emergency fund before taking significant investment risks. However, the exact approach can vary.
Someone with stable employment, low expenses, and strong financial reserves may have a different situation from someone with irregular income or substantial debt.
Before investing, consider whether you have enough accessible money for foreseeable short-term needs and whether high-interest debt needs attention.
Saving Plans for Beginners
Beginners can start with a simple savings plan rather than creating a complicated financial system.
First, calculate your monthly income and essential expenses. Then identify a realistic amount that can be saved regularly.
Automating the transfer can make the process easier. Instead of waiting to see how much money remains at the end of the month, move your planned savings amount shortly after receiving income.
Over time, increase the amount when your income rises or expenses decrease.
The most important objective for beginners is developing consistency.
Investment Plans for Beginners
Beginners should avoid investing money in products they do not understand.
Before making an investment, learn how the product works, what can cause its value to increase or decrease, what fees apply, and how easily you can access your money.
Diversification can also be an important concept. Rather than concentrating all your money in one asset, diversification spreads investments across different assets or sectors. It can reduce the impact of a poor performance from one investment, although it cannot eliminate investment risk.
Beginners should also be cautious about making investment decisions based on social media trends, rumors, or promises of fast profits.
The Role of Time in Saving and Investing
Time affects both saving and investing, but it plays a particularly important role in long-term investing.
When money remains invested for a long period, returns may potentially generate additional returns. This concept is commonly referred to as compound growth.
For example, if an investment generates earnings and those earnings remain invested, the amount available for future growth can increase.
However, compounding does not eliminate investment risk. The value of an investment can still fall, and future returns are uncertain.
Saving also benefits from time because consistent contributions can gradually build a larger financial reserve.
Inflation and Purchasing Power
Inflation is another factor to consider when comparing saving plans and investment plans.
Inflation means that the general price level of goods and services increases over time. As prices rise, the purchasing power of a fixed amount of money can decline.
Savings can provide stability and liquidity, but if the interest earned is below inflation for an extended period, the real purchasing power of the money may decrease.
Investments are sometimes used as a long-term strategy to seek returns that may exceed inflation, but they also involve risk.
Therefore, financial planning often requires balancing safety, accessibility, and potential growth.
Saving vs. Investing for a House
Buying a home can involve several financial stages.
Money needed for a near-term down payment or other upcoming home-buying expenses may be kept in savings or other relatively stable products, depending on the person’s circumstances and timeline.
If buying a home is many years away, some people may consider investing part of their money, depending on their ability to tolerate market fluctuations.
The closer the purchase becomes, the more important it may be to consider how much risk you can afford with money that will soon be needed.
Saving vs. Investing for Retirement
Retirement is generally a long-term goal, which makes investment planning an important consideration for many people.
Retirement accounts and investment portfolios can provide opportunities for long-term growth, depending on the available products and local regulations.
At the same time, retirees may need accessible savings for emergencies and near-term expenses.
A balanced retirement strategy can therefore involve both investments and cash savings.
The appropriate allocation can change as someone moves closer to retirement.
Saving vs. Investing for Education
Education goals can have different time horizons.
If tuition is due soon, keeping the money in an accessible savings product may be appropriate because the money will be needed shortly.
For education expenses that are many years away, families may have more options to consider, depending on their circumstances and risk tolerance.
The key question is not simply whether saving or investing is better. Instead, consider when the money will be needed and how much fluctuation you can accept.
How Risk Tolerance Affects Your Decision
Risk tolerance describes how comfortable you are with the possibility of losing money or seeing the value of an investment decline.
Some people are comfortable with substantial short-term fluctuations because they have long-term goals. Others may prefer greater stability.
Your ability to take risk also matters. Someone with unstable income or significant short-term financial obligations may have less ability to accept investment losses than someone with substantial financial reserves.
Understanding both your emotional comfort with risk and your financial capacity to take risk can help you make more appropriate decisions.
Common Mistakes When Choosing Between Savings and Investments
One common mistake is investing emergency money. If you need immediate access to cash, market volatility can create problems.
Another mistake is keeping all long-term money in cash without considering inflation and long-term financial objectives.
People can also make the mistake of chasing high returns without understanding the risks involved.
Another problem is failing to consider fees. Account charges, investment management fees, transaction costs, and other expenses can affect long-term results.
Finally, some people choose financial products based on recommendations from friends or social media without researching whether the product is appropriate for their own circumstances.
How to Build a Balanced Financial Plan
A balanced financial plan begins with understanding your current financial position.
Calculate your income, essential expenses, debts, savings, and financial goals.
Next, identify goals based on time horizon. Short-term goals may require accessible savings, while long-term goals may have more room for investment strategies.
Build an emergency reserve and establish a regular savings habit.
Once your basic financial foundation is established, you can evaluate long-term investment opportunities that fit your goals and risk tolerance.
Review your financial plan regularly because your income, expenses, responsibilities, and goals can change.
Saving Plans vs. Investment Plans: Which One Should You Choose?
The answer depends on what you are trying to accomplish.
If you need money soon and cannot afford a significant decline in its value, a savings strategy may be more appropriate.
If your goal is many years away and you can tolerate fluctuations, an investment strategy may provide opportunities for long-term growth.
For many people, the most practical approach is not to choose only one. Savings and investments can serve different purposes within the same financial plan.
Savings can provide the financial cushion needed for emergencies and short-term goals, while investments can be used for longer-term objectives.
Final Thoughts
Understanding the difference between saving plans and investment plans is an important part of financial education. Saving generally focuses on protecting money, maintaining accessibility, and preparing for short-term needs. Investing generally focuses on long-term growth and may involve greater risk.
Neither strategy is automatically appropriate for every financial goal. The right approach depends on factors such as your time horizon, income, expenses, emergency needs, debt, risk tolerance, and future objectives.
A practical financial strategy can include both savings and investments. You might use a savings account for emergency expenses and short-term goals while investing money intended for long-term objectives such as retirement.
Before choosing a financial product, understand its risks, fees, access conditions, potential returns, and relevant rules in your country. Do not assume that higher potential returns are guaranteed, and do not invest money that you may need immediately.
The most important step is to give your money a purpose. Once you understand whether a financial goal is short-term, medium-term, or long-term, it becomes easier to decide whether saving, investing, or a combination of both fits that goal.
By learning the difference between saving plans and investment plans and using each for appropriate purposes, you can create a more organized approach to managing your money and working toward your financial goals.