Saving Plans for Beginners: A Complete Guide to Building Wealth
Building wealth does not happen overnight. It is usually the result of consistent saving, thoughtful financial planning, disciplined spending, and making informed decisions over time. For beginners, the idea of managing money and creating a saving plan can seem complicated. However, you do not need to be a financial expert to start building a stronger financial future. Understanding basic saving principles and developing good money habits can provide a solid foundation for long-term financial security.
A saving plan gives your money a purpose. Instead of spending everything you earn, you decide how much money should be reserved for emergencies, future purchases, investments, education, retirement, and other financial goals. With a well-organized approach, even relatively small savings can become meaningful over time.
This complete guide to saving plans for beginners explains how to start saving money, create realistic financial goals, build an emergency fund, choose suitable savings accounts, manage expenses, understand compound growth, and gradually move from saving toward long-term wealth building.
What Is a Saving Plan?
A saving plan is a structured method of setting aside a specific amount of money regularly for future needs or financial goals. The plan can be simple or detailed depending on your income, expenses, and objectives.
For example, a beginner might decide to save a fixed amount from every paycheck. The money could be placed in a separate savings account rather than being kept in the account used for everyday spending. Over time, these regular contributions can create an emergency fund or help finance a specific goal.
A saving plan can also involve several accounts or financial products. You might have one account for emergency savings, another for short-term goals, and a long-term investment account for retirement. The important point is to give your money a clear purpose and create a system that you can maintain consistently.
Why Saving Money Is Important
Saving money provides financial flexibility. Unexpected expenses can happen at any time, and having money set aside can reduce the need to rely on credit cards, loans, or other forms of borrowing.
Savings can also help you achieve major financial goals. Buying a vehicle, paying tuition, starting a business, purchasing a home, or taking a planned vacation can become easier when you prepare for these expenses in advance.
Another important benefit of saving is peace of mind. Knowing that you have money available for emergencies can reduce financial pressure and make it easier to handle unexpected situations.
Saving is also the first step toward investing and building long-term wealth. Once you have established a stable financial foundation, you may be able to allocate some of your money toward investments designed for long-term growth.
Start by Understanding Your Financial Situation
Before creating a saving plan, you need to understand where your money currently goes. Start by calculating your monthly income and listing your regular expenses.
Essential expenses may include housing, food, utilities, transportation, education, insurance, debt payments, and other necessary costs. You should also identify discretionary spending such as entertainment, dining out, subscriptions, shopping, and hobbies.
Tracking your expenses for at least one month can reveal spending patterns that may otherwise go unnoticed. You may discover that several small purchases are taking up a significant portion of your income.
Once you understand your financial situation, you can determine how much money is realistically available for savings.
Set Clear Financial Goals
One of the most important steps in creating a saving plan is setting clear financial goals. Instead of simply deciding to “save money,” identify exactly what you are saving for.
Your goals might include building an emergency fund, purchasing a car, paying for education, saving for a home, starting a business, traveling, or preparing for retirement.
Each goal should ideally have a target amount and a deadline. For example, instead of saying, “I want to save for a car,” you might set a target such as “I want to save $8,000 within two years.”
A specific goal allows you to calculate how much you need to save each month and gives you a way to measure your progress.
Create an Emergency Fund
An emergency fund should be one of the first priorities for beginners. It is money reserved for unexpected expenses rather than regular spending.
Emergencies could include medical expenses, urgent home repairs, vehicle repairs, temporary unemployment, or other unexpected financial responsibilities.
The appropriate amount depends on your individual circumstances. Someone with variable income or significant family responsibilities may need a larger emergency reserve than someone with stable income and fewer financial obligations.
Emergency savings should generally be kept in a relatively safe and accessible account. The goal is to make the money available when you need it.
Building an emergency fund may take time, so do not become discouraged if you cannot save a large amount immediately. Starting with smaller contributions and increasing them gradually can still help establish the habit.
Follow a Realistic Budget
A budget is one of the most useful tools for beginners who want to improve their saving habits. A budget helps you understand how much money comes in, how much goes out, and how much can be allocated toward savings.
There are different budgeting methods, and no single method works for everyone. Some people prefer assigning specific amounts to different spending categories, while others use percentage-based approaches.
The key is to create a budget that reflects your actual financial situation. If your budget is too restrictive, it may become difficult to maintain.
Start by covering essential expenses, allocating money toward savings and debt repayment, and then determining how much remains for discretionary spending.
Pay Yourself First
The “pay yourself first” strategy means setting aside your savings before spending money on non-essential purchases.
For example, when you receive your salary, you can transfer a predetermined amount directly into your savings account. The remaining money is then available for expenses.
This approach can make saving more consistent because you are treating savings as an important financial responsibility rather than something that happens only if money remains at the end of the month.
You can make this process easier by setting up an automatic transfer through your bank.
Automate Your Savings
Automation is particularly helpful for beginners because it removes the need to remember to save every month.
You can arrange for a fixed amount to be transferred from your main account to your savings account immediately after receiving your income.
For example, if you decide to save $200 each month, you can schedule an automatic transfer for the day after your salary arrives.
Automation can turn saving into a routine. Over time, you may become accustomed to living on the money remaining after the transfer.
However, make sure the automatic amount is realistic. If the transfer causes you to fall short of essential expenses, adjust the amount.
Choose the Right Savings Account
Where you keep your savings matters. Beginners often use a standard savings account, but other options may be available depending on the country and financial institution.
A high-yield savings account may offer a higher interest rate than a basic savings account. Fixed-term deposits may offer different returns in exchange for keeping money deposited for a specific period.
When comparing savings accounts, look at the interest rate, fees, minimum balance requirements, withdrawal conditions, accessibility, and deposit protection.
Do not choose an account simply because it advertises the highest rate. Make sure its terms match your financial goals.
Understand Interest and Compound Growth
Interest is an important concept for anyone learning about personal finance. When a financial institution pays interest on your savings, your balance can increase over time.
Compound growth occurs when your accumulated earnings remain invested or deposited and begin generating additional earnings. This can make a significant difference over long periods.
For example, if your savings earn interest and you leave the interest in the account instead of withdrawing it, the balance can gradually grow through both your contributions and accumulated interest.
Compounding becomes particularly powerful when you give your money a long time to grow. This is one reason starting a saving and investing habit early can be valuable.
Control Unnecessary Spending
Saving more money does not always require earning more money. Reducing unnecessary spending can also increase the amount available for savings.
Review recurring expenses such as subscriptions, memberships, frequent restaurant visits, online shopping, and other discretionary purchases.
This does not mean you need to eliminate everything you enjoy. Instead, identify spending that provides little value to you and consider redirecting part of that money toward your financial goals.
Small changes can become significant when maintained over many months.
Reduce High-Cost Debt
Debt management is an important part of building wealth. High-interest debt can make it difficult to grow your savings because a significant portion of your income may go toward interest charges.
If you have expensive debt, consider creating a plan to reduce it while maintaining an appropriate level of emergency savings.
The best strategy depends on your financial circumstances. Some people prioritize paying the highest-interest debt first, while others prefer approaches that focus on smaller balances.
Reducing costly debt can eventually free up money that can be redirected toward savings and long-term investing.
Save for Short-Term Goals
Short-term savings are designed for goals you expect to achieve within a relatively short period.
Examples include a vacation, new computer, vehicle repair, annual insurance payment, or upcoming educational expense.
For short-term goals, preserving the money and maintaining access are often more important than pursuing high investment returns.
A separate savings account or savings category can make it easier to track your progress toward each goal.
Save for Long-Term Goals
Long-term goals require a different approach. Examples include retirement, purchasing a home, or building long-term wealth.
Because these goals may be many years away, you may have more flexibility to consider investments in addition to traditional savings.
Investments can potentially provide higher long-term returns than cash savings, but they also carry risk. The value of investments can rise and fall, and returns are not guaranteed.
Before investing, consider your timeline, risk tolerance, financial situation, and investment knowledge. Diversification can also help spread risk across different investments.
Understand the Difference Between Saving and Investing
Saving and investing are related but different financial strategies.
Saving generally involves keeping money in relatively stable and accessible accounts. The primary goals are security, liquidity, and preservation of money.
Investing involves purchasing assets with the expectation that they may increase in value or generate income over time. Examples can include stocks, bonds, mutual funds, exchange-traded funds, and other investments.
Investments can provide greater growth potential but can also lose value. Therefore, money needed for emergencies or near-term expenses may be better suited to savings rather than volatile investments.
Understanding this difference can help beginners avoid putting money at unnecessary risk.
Diversify Your Long-Term Investments
As you become more comfortable with personal finance, you may decide to invest some of your long-term savings.
Diversification means spreading your investments across different assets rather than putting all your money into one investment.
For example, a diversified portfolio might contain a combination of stocks and bonds or different types of funds. The exact mix depends on your goals and risk tolerance.
Diversification does not eliminate investment risk, but it can help reduce the impact of poor performance from a single investment.
Beginners should take time to understand investment products before putting money into them.
Consider Inflation
Inflation can affect the purchasing power of your savings. As prices increase, the same amount of money may buy fewer goods and services in the future.
This is especially important for long-term financial planning. If your savings earn a return that is lower than inflation, your money may lose purchasing power over time.
For short-term goals and emergency funds, stability and accessibility may remain the main priorities. For long-term wealth building, some people consider investments that have greater potential to outpace inflation, although these involve risk.
Understanding inflation can help you make more realistic long-term financial plans.
Increase Your Savings as Your Income Grows
When your income increases, consider increasing your savings contribution rather than automatically increasing your spending.
For example, if you receive a salary increase, you could direct part of the additional income toward your emergency fund, retirement savings, or other financial goals.
This strategy can help prevent lifestyle inflation, which occurs when spending increases as income increases.
You can still enjoy some of your additional income while using a portion to strengthen your financial position.
Create Multiple Savings Goals
As your financial situation improves, you may have several goals at the same time.
You might be building an emergency fund while saving for a car and contributing toward retirement.
Keeping these goals separate can make your finances easier to manage. You could use separate accounts, sub-accounts, or budgeting categories depending on the tools available to you.
Having clearly defined categories also makes it easier to determine whether you are making progress.
Review Your Financial Plan Regularly
Your saving plan should evolve as your life changes. A plan created when you are starting your career may need to change when you purchase a home, start a family, change jobs, or experience a significant change in income.
Review your budget and savings goals regularly. Check whether your contributions are still realistic and whether your financial products remain appropriate.
You should also review account fees, interest rates, investment performance, and changes in your financial objectives.
Regular reviews help ensure that your financial strategy remains relevant.
Common Saving Mistakes Beginners Should Avoid
One common mistake is waiting until the end of the month to save whatever money remains. In many cases, there may be little left after regular spending.
Another mistake is setting unrealistic savings targets. If the target is too high, you may struggle to maintain the plan.
Ignoring emergency savings is another problem. Focusing entirely on long-term investments without maintaining accessible emergency funds can create difficulties when unexpected expenses occur.
Beginners should also avoid making financial decisions based entirely on social media trends or promises of quick wealth. There is no guaranteed shortcut to building sustainable wealth.
Finally, avoid putting all your money into one investment without understanding the risks involved.
How Beginners Can Start Saving Today
Starting a saving plan does not require a large amount of money. Begin by reviewing your income and expenses and identifying a realistic amount that you can save regularly.
Open or designate a separate savings account if appropriate. Set a specific goal and automate your contribution.
For example, you could begin by saving a small fixed amount every week or month. Once you become comfortable with the habit, gradually increase your contribution.
The most important thing is to start. Developing a consistent financial habit can be more valuable than waiting until you have a large amount of money available.
Saving Plans and Building Long-Term Wealth
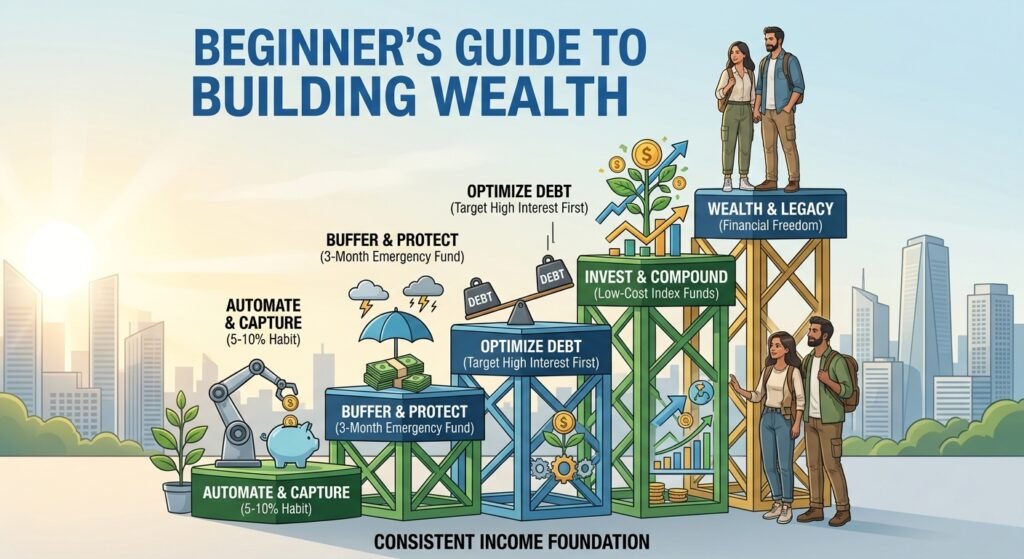
Saving is the foundation of financial stability, while investing can become a tool for long-term wealth building. A balanced financial strategy can include both.
First, focus on creating financial stability through budgeting, emergency savings, and responsible debt management. Once these areas are under control, you can consider investing money that you will not need in the near future.
Long-term wealth building requires patience. Financial markets can fluctuate, and investment values can change over time. Avoid making decisions based solely on short-term market movements.
Consistent contributions, diversification, controlling costs, and maintaining a long-term perspective can all play important roles in a wealth-building strategy.
Final Thoughts
Creating a saving plan is one of the simplest ways for beginners to take control of their finances. You do not need a large salary or advanced financial knowledge to begin. What matters most is having clear goals, creating a realistic budget, saving consistently, and gradually improving your financial habits.
Start by understanding your income and expenses. Set specific financial goals and create an emergency fund. Choose savings accounts that match your needs, automate your contributions, and control unnecessary spending.
As your financial foundation becomes stronger, learn about investing and consider appropriate long-term strategies for your circumstances. Remember that investments involve risk and that building wealth is a long-term process rather than a quick result.
The most effective saving plans for beginners are practical, consistent, and connected to real financial goals. Whether you are saving your first $100 or working toward a large long-term target, every contribution can become part of a broader financial strategy.
By starting today and maintaining good financial habits, you can create a stronger foundation for future opportunities. Saving money is not simply about having more money in the bank; it is about creating financial security, preparing for the future, and giving yourself greater control over your financial life.