How to Choose the Best Saving Plan for Your Financial Goals
Saving money is an essential part of building financial security and achieving important life goals. Whether you want to create an emergency fund, purchase a home, pay for education, plan a vacation, start a business, or prepare for retirement, choosing the right saving plan can make your financial journey easier and more organized. However, with so many savings accounts, fixed-term deposits, investment options, and financial products available, deciding where to put your money can sometimes feel confusing.
The best saving plan for your financial goals is not necessarily the account offering the highest interest rate. The right choice depends on several factors, including your financial goal, time frame, income, expenses, accessibility requirements, risk tolerance, and expected return. Understanding these factors before choosing a savings product can help you make a more informed financial decision.
In this guide, we will explain how to choose the best saving plan for your financial goals, what features to compare, how to match savings products with short-term and long-term objectives, and which common mistakes you should avoid.
What Is a Saving Plan?
A saving plan is a structured approach to setting aside money regularly for a specific financial purpose. It can involve a traditional savings account, high-yield savings account, fixed-term deposit, recurring deposit, retirement account, education fund, or a combination of savings and investments.
The main purpose of a saving plan is to help you develop financial discipline while gradually building funds for future needs. Instead of spending all of your income, you allocate a specific amount toward savings according to your financial priorities.
A good saving plan usually includes a target amount, a deadline, a regular contribution, and a suitable place to keep the money. For example, if you want to build an emergency fund of $6,000 within one year, you can calculate the approximate monthly contribution required and choose an account where the money remains relatively accessible.
Why Choosing the Right Saving Plan Matters
Choosing the right saving plan can affect how quickly you reach your financial goals. Different savings products have different interest rates, fees, withdrawal rules, maturity periods, and levels of risk.
For example, an emergency fund generally needs to be accessible because you may need the money unexpectedly. A retirement fund, on the other hand, may have a much longer time horizon, allowing you to consider financial products designed for long-term growth.
Using the wrong type of account can make your financial plan less effective. You might put short-term money into an account with withdrawal restrictions or keep long-term savings in an account that earns very little interest.
Understanding the purpose of your savings before selecting a financial product can help you make a more suitable choice.
Step 1: Define Your Financial Goal
The first step in choosing the best saving plan is to clearly define what you are saving for. A vague goal such as “I want to save more money” does not provide enough information to create an effective plan.
Instead, create a specific goal. You might want to save $5,000 for a car, $10,000 for education, $20,000 for a home down payment, or several months of living expenses for emergencies.
A specific goal gives you a target to work toward. It also makes it easier to calculate how much you need to save each month.
For example, if your goal is to save $12,000 in two years, you would need to save approximately $500 per month before considering interest or investment returns. This simple calculation can help you determine whether your target is realistic based on your income and expenses.
Step 2: Determine Your Savings Time Frame
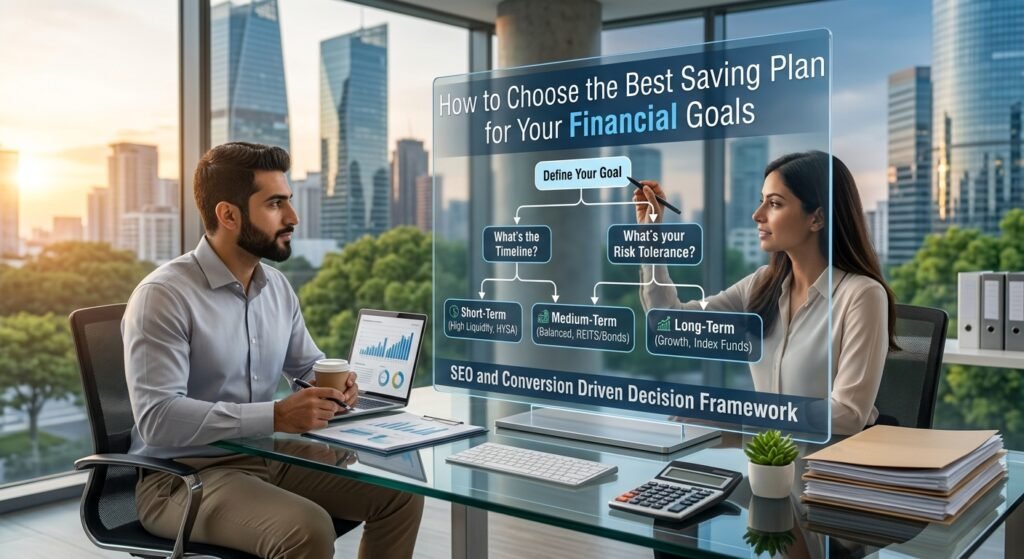
Your financial timeline is one of the most important factors when choosing a saving plan. Financial goals can generally be divided into short-term, medium-term, and long-term goals.
Short-term goals may be goals you expect to achieve within a few months or a few years. Examples include an emergency fund, vacation, vehicle purchase, or upcoming educational expense.
Medium-term goals may take several years, such as saving for a home, business, or major family expense.
Long-term goals can extend over many years and often include retirement and long-term wealth building.
The longer your time frame, the more options you may have for considering products designed for growth. However, longer-term investments can also involve greater fluctuations and risks. Money that you need soon generally requires greater emphasis on stability and accessibility.
Step 3: Calculate How Much You Can Save
Before selecting a saving plan, examine your current financial situation. Calculate your monthly income and subtract essential expenses such as housing, food, transportation, utilities, education, debt payments, and other necessary costs.
The amount remaining after essential expenses gives you a starting point for determining how much you can save. However, you should also allow room for unexpected expenses and personal spending.
It is usually better to choose a realistic savings amount that you can maintain consistently rather than setting an unrealistic target that forces you to stop saving after a few months.
Even a modest monthly contribution can become meaningful when maintained consistently over a long period.
Step 4: Build an Emergency Fund First
Before focusing heavily on long-term financial goals, consider building an emergency fund. An emergency fund provides a financial cushion for unexpected expenses and can reduce the need to rely on high-cost borrowing when something goes wrong.
The appropriate size of an emergency fund depends on your personal circumstances. Factors such as job stability, income variability, family responsibilities, debt, and monthly expenses can influence how much you need.
Emergency savings should generally be kept in a relatively safe and accessible account. The goal is to have money available when you need it rather than maximizing investment returns.
Once your emergency savings are established, you can focus more confidently on other financial goals.
Step 5: Compare Interest Rates and Returns
Interest rates are an important factor when comparing saving plans. A higher interest rate can help your money grow faster, particularly when savings are held for an extended period.
However, you should not choose a financial product based solely on its advertised rate. Check whether the rate is fixed or variable, whether promotional rates expire, and whether certain balance requirements apply.
For investment products, understand that potential returns are not necessarily guaranteed. Investments can increase or decrease in value, and higher potential returns generally come with greater risk.
When comparing products, consider the actual return after fees, taxes, and other costs where applicable.
Step 6: Understand Compound Growth
Compound growth is an important concept for long-term saving. When your savings earn interest or investment returns and those earnings remain invested, future returns may be generated on the original amount as well as previous earnings.
For example, if you save money in an account that pays interest and leave the interest in the account, your balance can gradually increase through both contributions and accumulated interest.
The longer you allow money to grow, the more significant the effect of compounding can become. This is one reason starting a savings plan early can be beneficial.
However, the actual growth rate depends on the financial product, interest rate, fees, taxes, and market performance where investments are involved.
Step 7: Consider Accessibility
Accessibility refers to how easily you can withdraw or use your money. This is an important consideration when choosing a savings plan.
If you are building an emergency fund, you may want an account that allows relatively easy access. If you are saving for a goal several years away, you might be comfortable with a product that limits withdrawals in exchange for potentially different returns or terms.
Some fixed-term savings products may charge a penalty or reduce the return if you withdraw money before the maturity date.
Always understand the withdrawal rules before depositing money. Keeping money in an account that does not match your access requirements can create problems when you need it.
Step 8: Check Fees and Charges
Fees can reduce the amount of money you ultimately earn. Some financial products may charge account maintenance fees, withdrawal fees, transaction fees, management fees, or penalties.
A product with a slightly higher advertised interest rate may not necessarily provide a better overall result if it also has significant fees.
Before opening an account, read the terms and conditions carefully. Look for minimum balance requirements, monthly fees, early withdrawal penalties, and other charges.
Understanding the complete cost of a financial product can help you compare options more accurately.
Step 9: Consider Inflation
Inflation refers to the general increase in prices over time. As prices rise, the purchasing power of money can decrease.
For example, if your savings earn a return of 3% while inflation is 5%, your money may increase in nominal value but lose purchasing power in real terms.
This is particularly important for long-term financial goals. A savings strategy that works for a short-term objective may not be sufficient for a goal that is several decades away.
For long-term goals, some people consider a combination of savings and investments to potentially achieve higher growth. However, investments involve risks, and returns are not guaranteed.
Step 10: Match the Saving Plan to Your Risk Level
Risk tolerance is another important factor. Some people prefer the stability of traditional savings products, while others are comfortable with investments that can fluctuate in value.
If losing money would make it difficult for you to meet an important financial obligation, you may want to prioritize lower-risk options for that particular goal.
For long-term goals, you may have more time to tolerate market fluctuations, but your personal circumstances and comfort with risk still matter.
There is no universal risk level that is appropriate for everyone. Your financial goals, income, age, responsibilities, and timeline should all be considered.
Best Saving Plans for Short-Term Goals
Short-term financial goals generally require stability and accessibility. Examples include an emergency fund, vacation, upcoming tuition payment, wedding expenses, or a planned purchase.
For these goals, traditional savings accounts, high-yield savings accounts, and certain short-term deposits may be suitable depending on the products available in your country.
The key consideration is that the money should be available when the goal arrives. Taking significant investment risk with money you will need soon can create a problem if the value declines at the wrong time.
Focus on protecting the money and maintaining sufficient access rather than simply searching for the highest possible return.
Best Saving Plans for Medium-Term Goals
Medium-term goals may include purchasing a car, preparing a home down payment, starting a small business, or paying for future education.
Because these goals may be several years away, you may have more flexibility in choosing financial products. Depending on the timeline, you could consider savings accounts, fixed-term products, or a combination of savings and appropriate investments.
The exact choice depends on how much risk you can accept and how important it is to preserve the money for a specific deadline.
If your goal has a fixed date, such as a tuition payment or property purchase, make sure your strategy does not expose the required funds to unnecessary short-term volatility.
Best Saving Plans for Long-Term Goals
Long-term goals such as retirement and long-term wealth building provide a longer period for your money to potentially grow.
Traditional savings accounts can still have a role in long-term financial planning, particularly for emergency reserves or short-term portions of a portfolio. However, depending on your circumstances, some people also use diversified investments for long-term goals.
Long-term investing can provide opportunities for growth but also involves market risk. The value of investments can fall, sometimes significantly, and there are no guaranteed returns for many investment products.
A long-term plan should therefore consider diversification, fees, taxes, risk tolerance, and the time until the money is needed.
Automate Your Savings
One of the easiest ways to maintain a saving plan is to automate your contributions. You can arrange an automatic transfer from your main account to your savings account after receiving your income.
Automation helps turn saving into a routine rather than something you have to remember every month.
For example, if you decide to save 10% of your monthly income, you can arrange for that amount to be transferred automatically. You can adjust the amount later as your income or expenses change.
Automation can be particularly helpful for people who find it difficult to save what remains at the end of the month.
Use Separate Accounts for Different Goals
Keeping all your savings in one account can make it difficult to understand how much money is available for each goal.
Consider creating separate savings categories for different purposes. You could have an emergency fund, vacation savings, education savings, and long-term savings.
Separating your goals can make financial progress easier to track. It can also reduce the temptation to spend money that has already been allocated to an important objective.
Many modern banking platforms allow users to create separate savings spaces or categories, although the specific features vary by institution.
Review Your Saving Plan Regularly
Financial planning should not be a one-time activity. Your income, expenses, responsibilities, and goals can change over time.
Review your saving plan periodically to determine whether your contributions are still appropriate. If your income increases, you may be able to increase your savings. If your expenses rise, you may need to adjust your monthly contribution.
You should also review the interest rates, fees, and terms of your savings products. Financial institutions may change their rates or product conditions.
Regular reviews help keep your saving plan aligned with your current financial situation.
Common Mistakes When Choosing a Saving Plan
One common mistake is choosing an account simply because it offers the highest interest rate. The rate may be promotional, require a minimum balance, or come with restrictions that do not suit your needs.
Another mistake is ignoring fees. Even small recurring charges can reduce your savings over time.
Some people also fail to consider their timeline. Putting short-term money into volatile investments can create difficulties if the market declines before the money is needed.
Another mistake is setting an unrealistic savings target. A plan that requires you to sacrifice essential expenses is unlikely to remain sustainable.
Finally, failing to review your savings plan can cause you to miss better opportunities or continue using a product that no longer matches your goals.
How to Create a Simple Saving Plan
Creating a simple saving plan does not have to be complicated. Begin by writing down your financial goal and target amount. Then determine when you need the money.
Next, calculate how much you can realistically contribute each month. Divide your target by the number of months available to get a basic contribution target.
Choose a savings product that matches the goal’s timeline, accessibility requirements, and risk level. Set up automatic contributions if possible.
Track your progress every month and make adjustments when your circumstances change.
For example, if your goal is to save $6,000 over one year, you could aim to contribute approximately $500 per month before considering interest. If your income increases during the year, you might increase your monthly contribution and reach your target sooner.
Final Thoughts
Choosing the best saving plan for your financial goals begins with understanding what you want to achieve and when you will need the money. There is no single savings product that is ideal for every person or every financial goal.
Short-term goals generally require accessibility and stability, while long-term goals may provide more opportunities to consider products designed for growth. Emergency funds should generally be easy to access, while retirement savings can be planned over a much longer period.
When comparing saving plans, consider interest rates, potential returns, fees, accessibility, inflation, taxes, risk, and the time horizon of your goal. Most importantly, choose a plan that you can maintain consistently.
A successful saving strategy is built on clear goals and good financial habits. By creating a realistic budget, automating your savings, separating money for different objectives, and reviewing your plan regularly, you can make steady progress toward your financial goals.
The right saving plan is ultimately the one that fits your individual circumstances and helps you balance financial growth with security and accessibility. Start with one clear goal, take consistent steps, and adjust your strategy as your financial situation develops.